Tuesday, November 30, 2010

NEW Foreclosure Prevention Service Map

Over the past few years of the foreclosure crisis in Minnesota, both housing industry professionals and social service agencies have requested an easy-to-use map of service areas covered by the Center's network of foreclosure counseling agencies... that they could print out and keep handy.

Now, the Center has produced a new printable map showing foreclosure counseling services provided by the Homeownership Advisors Network and the geographic or language service area they cover. This map is intended to be a reference tool for professionals as a supplement to the interactive online map.


(Click To Enlarge - Use Link Below For High Quality Print Version)

The map is available for download (print) here. 

The same information is also available in an interactive format here.

There are also other resources (including fact sheets, presentations, newsletters and more) available for professionals that may be working with struggling homeowners at the Center's website here.

Foreclosure prevention counseling services are provided free of charge by nonprofit housing counseling agencies working in partnership with the MN Home Ownership Center. Remember: there is no need to pay a private company for these services!  For more information an avoiding foreclosure, visit the Center's website.

Tuesday, November 23, 2010

Moving? Where are you going?

I came across a great interactive map from Forbes the other day (yes, they published the map a few months ago... but the information is great).  If you click on any county on the map it will show you the inbound and outbound movement for that county... including lines that show where people are moving to and from.

On the map... RED lines show the out-migration* from the county and in-migration* is shown in DARK GREY/Black for households that moved in 2008.  While the data is a few years old... there's no reason to think that the trend would have changed too dramatically in the last year and a half.

As an example, here's the migration map for Ramsey County:


(Click To Enlarge)

If you want to see a REALLY scary picture... click on Detroit (Wayne County, MI).

The interactive map is here.


*NOTE:  I've chosen to use the terms out-migration and in-migration instead of Emigration and Immigration... as those terms tend to refer to movement outside/into the country. The movements represented on the Forbes map show the movement of US residents only to and from OTHER US counties.

Monday, November 22, 2010

Center Board Member Recognized: Top Woman in Finance

The Minnesota Home Ownership Center is proud to publicize the fact that Muffie Gabler, long-time Center board member, has been recognized by Finance and Commerce as one of only 50 “Top Women in Finance” in Minnesota. In addition, Muffie was chosen to join Finance and Commerce’s “Circle of Excellence” as she had previously been honored as a Top Woman in Finance in 2007.

The Top Women in Finance award is given to principals, partners, executive vice presidents, CFOs, CEOs and managing directors at not only financial institutions and lenders but also leaders of businesses small and large throughout Minnesota who have shown innovation, leadership, or some other notable qualities in the area of finance.

In addition to being one of the principal drivers of the creation of the Minnesota Home Ownership Center, Muffie has been an integral part of the Affordable Housing arena in Minnesota and countless affordable housing initiatives and community development projects would never have gotten off the ground without Muffie’s assistance.

Winners were recognized during a dinner and program on November 10th at the Hyatt Regency in Minneapolis. For a complete list of honorees, visit the Finance and Commerce article here.

Thursday, November 18, 2010

Pre-Foreclosure Notices Continue Unabated

The Minnesota Home Ownership Center has compiled the pre-foreclosure notices received by the statewide network of Housing Counselors through the end of the third quarter (September)... and the upward trend continues!

The most recent quarter (July through September) recorded the second-highest number of pre-foreclosure notices since the MN legislature enacted the notices in the third quarter of 2008.  Year-To-Date, the total number of pre-foreclosure notices received has now exceeded 54,000.

(Click To Enlarge)

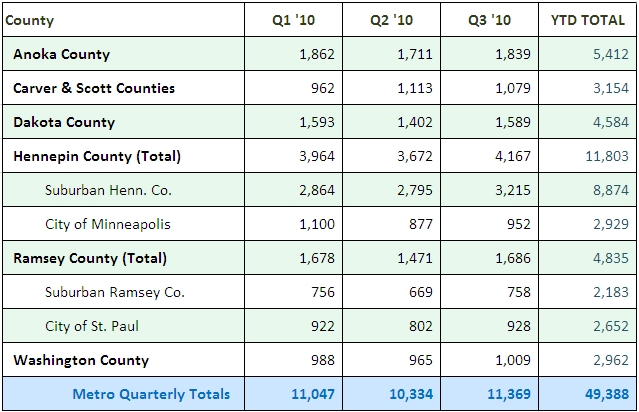
Here's the breakdown for the number of pre-foreclosure notices received by members of the Home Ownership Advisors Network in the 7-County Metro Area:

(Click To Enlarge)


NEW:  For the first time since the Center started tracking and publishing the pre-foreclosure notice totals in June of 2009, we are now tracking the running quarterly totals of notices received to see where the trend is heading: 

(Click To Embiggen)


This information makes it hard to forecast anything but continued foreclosure activity and continued mortgage difficulties for Minnesota families.  As always... if you're struggling with your mortgage payments - or think you might fall behind soon - don't wait!  There is a network of non-profit agencies that can help.  Contact them today.  For additional information about foreclosure prevention in Minnesota - visit the Center's foreclosure prevention resource page here.

Are HAMP Improvements Possible?

On Wednesday, November 17th, MN Senator Franken joined 17 other Senators in sending a letter to Treasury Secretary Timothy Geithner asking for immediate changes to the HAMP program to help homeowners facing foreclosure. 

The complete letter is here. (PDF Document)

Here are some of the key steps the Senator(s) recommend implementing in order to improve the HAMP program:
  • The creation of the Office of the Homeowner Advocate. This office would focus on assisting homeowners who believe their mortgage servicer is breaking the rules;
  • Provisions that would hold servicers accountable;
  • Automatically extend permanent mortgage modifications if trial modifications are completed successfully;
  • Revise eligibility requirements;
  • Ensure that servicers provide homeowners with necessary documentation; and
  • Provide homeowners with information as to why they have been denied HAMP modification.

The Minnesota Home Ownership Center applauds any and all efforts to assist struggling homeowners... and welcomes your comments as well!
  • Will Senator Franken's suggestions improve the HAMP program?
  • What improvements would YOU suggest to improve the HAMP program?
  • Do you have other suggestions for helping struggling MN homeowners?
Use the comments section to post your suggestions.

Tuesday, November 9, 2010

Fourth Annual EMHI Summit

The Minnesota Home Ownership Center is pleased to announce that the 2010 Emerging Markets Home Ownership Initiative (EMHI) summit has been scheduled for December 8, 2010 at the Continuing Education and Conference Center on the St. Paul Campus of the University of Minnesota.

The Annual EMHI Summit is a hallmark of the Center’s dedication to the EMHI mission of working to promote homeownership parity. This year's Summit will bring together industry and community stakeholders to develop tools, resources, and best practices aimed at increasing homeownership opportunities for Minnesota’s emerging markets.

The agenda will include:
  • A welcome from MN Home Ownership Center Executive Director Julie Gugin;
  • Michael Grover, community affairs manager from the Federal Reserve Bank of Minneapolis, and John Patterson, director of research and evaluation at Minnesota Housing, will provide a comprehensive analysis of the current status of emerging markets homeownership in Minnesota. A traditional part of the EMHI Summit, this presentation will offer thought-provoking insight into the status of emerging markets homeownership and how the current economic environment has impacted effort;
  • Representatives from the industry, including Michael A Haley, of Identity Theft Shield, Nancy Hostetler of Open Door Home Loans (Bell Mortgage) and Roxanny Armendariz of Neighborhood Development Alliance will offer practical insights into client credit issues facing members of emerging markets. Discussions will include credit repair and Fair Issac scoring;
  • Keynote Speaker: Angela Glover Blackwell (Pending)

    Angela Glover Blackwell is a national leader for social justice and equity. She seeks to strenghten America by creating stronger low-income communities and communities of color. A former Sr. vice president at the Rockefeller Foundation, she has appeared on Nightline, PBS's NOW, and is a frequent commentator on public radio's Marketplace and the Tavis Smiley Show. Her articles have appeared in the New York Times, the LA Times and the San Francisco Chronicle.
The Summit is designed primarily for realtors, lenders, non-profits, elected officials, and others working in the homeownership arena, but is open to all.

The Summit is FREE and 3.5 hours of Real Estate CEU credits have been applied for.

REGISTER TODAY: http://emhisummit2010.eventbrite.com

Are you on Twitter?  Help Spread The Word!  Use Hashtag #EMHI10  (EMHI TEN)

Thursday, November 4, 2010

Foreclosure Data - Another Blow

Lender Processing Services has released their most recent version of the LPS Mortgage Monitor, October 2010 Mortgage Performance Observations which contains an informative series of charts and graphs that show that while delinquent and foreclosed loans had stabilized somewhat at the end of 2009 and into the first half of 2010, new problem loans are once again picking up:


(Click To Enlarge)


The graph above shows loans that are currently 60 days or more delinquent but that were current just 6 months ago.  You can certainly see the upswing that started in the middle of 2010.

The LPS report also has some, albeit limited, information regarding Minnesota.  For example, in their table on the Delinquency and Foreclosure Rate, Minnesota ranks 42nd in the nation (that's a good thing!) in percentage of delinquent mortgages:


(Click to Enlarge)

According to the chart, our delinquency rate is about 34% lower than the national average of 9.27%.

Another chart that contains information about Minnesota shows that the average number of days delinquent for loans that are in foreclosure (time delinquent before foreclosure sale) has increased 85% since 2008, and now overages over a year - 386 days to be exact:


(Click To Enlarge)


Not only is it taking lenders/servicers longer to foreclose... the number of foreclosures is starting to increase again.  This problem is NOT going to go away soon.  Thousands of Minnesota families are still struggling every month to make their mortgage payments!  If you, or someone you know is struggling... don't wait, contact a member of the Minnesota Home Ownership Center's network of foreclosure counseling agencies TODAY.  The sooner you call, the more options you have available!

Tuesday, November 2, 2010

Vote Again!

No... the Minnesota Home Ownership Center is not advocating voter fraud!  :-)

We want you to vote on the consumer handout that we plan to produce for our Look Before You Leap campaign.

“Look Before You Leap” is a statewide public education campaign seeking to raise public awareness about the booming foreclosure rescue scam industry and its dangerous implications for struggling and unsuspecting home owners, and to connect struggling home owners with the Center’s network of FREE and trustworthy foreclosure counselors.

The piece we are designing will be used in mailings, handouts, counter displays, etc... and we hope to make the piece as attractive as possible so that struggling homeowners see the piece and respond.

Here are the two options:

(Click To Enlarge)


Would you take please take 30 seconds to respond to a quick on-line survey about the piece?  4 questions... 30 seconds... SURVEY HERE  

You can also leave feedback in the comments!  We'll be compiling this information through Friday, November 5th.  THANKS!

Thursday, October 21, 2010

What A Difference A Decade Makes

I recently came accross a report from the Federal Reserve Bank of San Fransisco entitled "Underwater Mortgages" where the authors,  John Krainer and Stephen LeRoy, attempt to determine the point at which underwater borrowers decide to throw in the towel and walk away from their homes.

While the article has some interesting information about the 'boiling point', I found that two of the images that accompany the report are just as interesting for people working in housing in Minnesota.

The first image shows the share of underwater mortgages in the fourth quarter of 2000:


(Click To Enlarge)

According to the figure, in the fourth quarter of 2000, Minnesota was one of only a dozen states where the share of 'underwater' mortgages was less than one tenth of one percent! (between 0% and 0.1%).


However, by fourth quarter 2009, our rate of negative equity homeowners had increased to between 6% and 10%:


(Click To Enlarge)

Interestingly... NO STATE was in the 0%-0.1% category by the end of the 'aughts'.

The complete report is here.

Tuesday, October 19, 2010

Residential Foreclosures in Minnesota Report

Minnesota Housing has just released the Summer 2010 version of its "Residential Foreclosures in Minnesota" report, based on delinquency and foreclosure information from EVERY Zip Code in the state (through June 2010)... and there is a ton of great information for real estate and lending professionals, municipalities and elected officials and others that are working on foreclosure prevention and remediation efforts.

The report is available online here.

Here are just a handful of the highlights of the report:
  • Although the number of sheriff sales in Minnesota dropped from 26,000 to 23,000 between 2008 and 2009, the 2009 level is dramatically higher than the 6,500 sales that occurred in 2005.2 In addition, the number of sheriff sales started to increase again in late 2009 and early 2010.3 Sheriff sales are expected to rise back up to the 26,000 level in 2010.
  • Between 2007 and 2010, the subprime market’s share of residential mortgages in foreclosure dropped from 54% to 25% in Minnesota.  During the same period, the prime market’s share increased from 40% to 60%.
  • There is concern about alt-A loans and option ARMs that will reset or recast in the next few years.

The report is full of great graphics that show exactly where the highest concentrations of delinquencies (60-day lates) and foreclosures are happening.  Here is the map of loans that are 60-days or more delinquent throughout the state of Minnesota:


(Click To Enlarge)


From this map alone... it is clear that the foreclosure crisis is continuing to move out of the core cities of Minneapolis and St. Paul, and into the outer ring communities just outside the seven-county metropolitan area, particularly in Wright, Sherburne, and Isanti counties.

The report also maps the prevalence of REO properties and homes in foreclosure (as of June, 2010).  In addition... the data is not just available in map form, but Minnesota Housing has included the information for EVERY Zip Code (where there are more than 200 residential parcels). 

Go ahead... go dig through the report... let us know if you find anything that surprises you.  Your comments are welcome!

Friday, October 8, 2010

Bank of America Halts Foreclosures in Minnesota

According to a press release on the Bank of America website, BoA has halted ALL foreclosure sales in all 50 states.  This, obviously, includes Minnesota.

The actual text of the press release is:
Bank of America has extended our review of foreclosure documents to all fifty states. We will stop foreclosure sales until our assessment has been satisfactorily completed. Our ongoing assessment shows the basis for our past foreclosure decisions is accurate. We continue to serve the interests of our customers, investors and communities. Providing solutions for distressed homeowners remains our primary focus.

The wording of their press release is interesting.  It states that they will halt "foreclosure sales" until they've finalized their internal reviews... but it does not state anything about the REST of the foreclosure process.  Will they continue all the steps PRIOR to the Sheriff's sale in Minnesota?  (For an overview of the steps, view our Foreclosure Process Infographic). 

Will other lenders follow suit?  Let us know what you think in the comments.

We will continue to monitor the situation... and let our readers know of updates as they become available.

Struggling homeowners should be aware that this decision by Bank of America will NOT, ultimately, end their financial crisis.  If you are struggling with payments - whether you are a Bank of America client or not, the best resource in Minnesota the MN Home Ownership Center's network of FREE Foreclosure Counselors.  These counselors can work with you to find individualized solutions to YOUR personal mortgage crisis and answer questions about how foreclosure related policies and programs affect you.  To find your closest counselor, click here.


UPDATE: We've received information from Bank of America... that specifically states that the ONLY part of the process that is halted is the actual sale date... and ONLY those sale dates that fall between October 9, 2010 and November 1, 2010:
First, I want to clarify that there is no moratorium in place. What we have done is postpone any scheduled foreclosure sales, that fall between 10/9 and 11/1 to a date after November 1st. This is to allow for additional time to complete necessary document reviews. All other foreclosure activity will continue as usual.

Thursday, October 7, 2010

Housing Counselor Training Opportunity

Homebuyer Counseling Training and Certification

The Minnesota Home Ownership Center is offering homebuyer counseling training and certification for housing professionals that provide pre-purchase counseling in Minnesota. This training will also help Real Estate agents that work with first-time homebuyers by sharing techniques, methods and practices to resolving any barriers that first-time buyers may have to homeownership.

Activities include determining mortgage readiness, prequalification, reviewing credit reports and many other key counseling/home buying components.

Participants interested in Continuing Education credits can pursue these through the "Self-Directed" option (Individual Continuin Ed Course Approval) through the MN Dept. of Commerce.  

Participants interested in obtaining certification must complete the training and pass the in-class exam.

For additional information or to register, click here.

Monday, October 4, 2010

Can lender access property after foreclosure sale?

This post is a guest post by attorney Jeffrey O'Brien, partner with Mansfield Tanick & Cohen, P.A. who specializes  in the areas of business and corporate law, real estate law, estate and business succession planning and probate law.

___________________________

Can a Foreclosing Lender Enter a Property
During the Redemption Period?

In Minnesota, foreclosures work a bit differently than other states. Not only does Minnesota have a non-judicial foreclosure process (unlike most states which only allow foreclosures to be brought by court action), but Minnesota is also one of only ten (10) states that provides for post-sale redemption rights.

The most significant implication of a foreclosed homeowner having post-sale redemption rights (as opposed to pre-sale redemption rights) is that the foreclosure sale does not end the process. In a way, it is only the beginning. For the next six (6) months, Minnesota law allows the homeowner to stay in possession of the property, with the understanding that up until the end of the six (6) months, the homeowner could, theoretically, pay off the foreclosing lender’s mortgage plus the costs of the foreclosure and regain ownership of the property.

This post-sale redemption period can be tricky, for a number of reasons. For example, the lender is not able to list the property for sale, based upon the fact that the homeowner can redeem the property during that period, and allowing the lender to sell the property to someone else would create a significant ownership dispute, not to mention the fact that there would seem to be little to no market for purchasing a property that could be redeemed at less than the new buyer’s purchase price for a period of time. For this reason, if the homeowner abandons the property, the lender has the option to seek a court-ordered shortening of the redemption period to five weeks.

Even if the redemption period is not shortened, the lender is not powerless to protect its property. That’s because Minnesota Statutes Section 582.031 allows the lender, in certain circumstances, to enter the property during the redemption period and take steps to protect the property. The statute provides that “if premises described in a mortgage or sheriff's certificate are vacant or unoccupied, the holder of the mortgage or sheriff's certificate or the holder's agents and contractors may, but is under no obligation to, enter upon the premises to protect the premises from waste, until the holder of the mortgage or sheriff's certificate receives notice that the premises are occupied.”

Subdivision 2 of the statute goes on to clarify what actions the lender may take to protect the premises from waste: “install or change locks on doors and windows, board windows, install an alarm system, provide a resident caretaker, and otherwise prevent or minimize damage to the premises from the elements, vandalism, trespass, or other illegal activities.” For example, given Minnesota’s harsh winters, a lender may take steps to ensure that pipes don’t freeze and burst by winterizing the property.

In order to protect the homeowner’s redemption rights (which include the right of possession of the property until the expiration of the owner’s redemption period), if the holder of the mortgage or sheriff's certificate installs or changes locks, a key to the premises must be promptly delivered to the homeowner or any person lawfully claiming through the mortgagor, upon request.

Section 582.031 is a necessary result of Minnesota’s post-sale redemption rights, and lenders should be aware of their rights during the redemption period just as much as they need to be concerned about the homeowner’s rights.
___________________________

This post was originally published on Jeff's blog: here. 
Reposted with permission.

For more information about your rights after a foreclosure sale - during Minnesota's Redemption Period - the Center has created a Redemption Period Fact Sheet, or you can visit the Center's website here.

HECAT Funding Awards Announced

The State of Minnesota is unique in that we are the only state in the country with a dedicated pool of funds that provides financial support to eligible non-profit organizations to deliver a variety of homebuyer/homeowner education, counseling and training services to Minnesotans. This dedicated pool is known as HECAT (The Homeownership Education, Counseling and Training Fund).

Some of the valuable services that are funded through HECAT include:
  • Pre-purchase education and counseling (Home Stretch),
  • Post-purchase education and counseling,
  • Home equity conversion counseling (Reverse Mortgages) and
  • Foreclosure counseling
Funds for HECAT come from four funding partners that are fully invested in ensuring that Minnesotans have access to the education and counseling tools necessary to achieve successful home ownership:
Each of the four funding partners not only contribute financial resources they also actively participate in the grant-making process.

Additional information about HECAT can be found here.

A complete list of organizations that have been granted HECAT funds for the 2010-2011 program year is available here. (PDF Document)


Friday, October 1, 2010

Open Position - Dakota County CDA

Interested in helping people begin or maintain sucessful homeownership?  Looking for a new career? 

The Dakota County Community Development Agency is seeking an experienced Homeownership professional to provide housing counseling services in the area of pre-purchase and mortgage default and foreclosure prevention. 

Duties include:  Conduct homebuyer education sessions; perform foreclosure program intake; conduct applicant interviews, determine eligibility, provide counseling services, respond to inquiries, and maintain records. 

Starting salary:  $3,284 - $3,542/mo. DOQ, plus benefits. 

This position is grant-funded through September 30, 2011 with future employment dependent on continued program funding.  Some evening and weekend hours may be required.  Requires 4 years related education and/or experience; Certified Mortgage Foreclosure Prevention Specialist preferred.  

Completed CDA application forms must be received in the CDA office by 4:30pm on October 20, 2010.  You can use their online application process here: www.dakotacda.org, or call their Jobs Line at (651) 675-4441.  The Dakota County CDA is an Equal Opportunity Employer

Thursday, September 30, 2010

Foreclosure Suspensions in Minnesota?

UDPATE:  Bank of America & PNC have halted foreclosures in ALL 50 states, including Minnesota.  If other lenders join them, we'll update this blog post.


Recently a number of stories have hit the media regarding certain servicers halting or suspending foreclosures due to issues (errors) with their internal document processing and legal procedures.  The servicing companies that have voluntarily issued moratoria are GMAC and JPMorgan Chase, although many other servicers are reviewing their procedures, and others may follow suit.


The question has arisen as to whether these foreclosure suspensions/moratoria will affect any Minnesota homeowners.  The short answer is: probably not.


The key reason is due to the fact that the vast majority of foreclosures in Minnesota follow a process known as Foreclosure by Advertisement, and not the process of judicial foreclosure (where a judge must enter a judgment of foreclosure against a homeowner before the house can be auctioned/sold).  In Minnesota, no such step is required if the servicer is pursuing Foreclosure by Advertisement.


For more information about the Foreclosure by Advertisement process, the MN Home Ownership Center has created a fact sheet that highlights the steps a lien holder must take to foreclose.  That document is here.


From the NY Times:
The lender, JPMorgan Chase, said on Wednesday that it was halting 56,000 foreclosures because some of its employees might have improperly prepared the necessary documents. All of the suspensions are in the 23 states where foreclosures must be approved by a court, including New York, New Jersey, Connecticut, Florida and Illinois.  [Emphasis ours]


The Center will continue to monitor the situation, and if other servicers join the ranks of GMAC and JPMorgan Chase, we'll update the blog.  In addition... if any servicers halt foreclosures in Minnesota, we'll highlight that information as well.


If you're struggling with your mortgage payments - no matter who your lender or servicer is - getting help as soon as possible is key.  There is a network of FREE, non-biased, non-profit Housing Counselors that specialize in foreclosure prevention.  To locate your closest counselor, visit the MN Home Ownership Center's website, here.

Monday, September 27, 2010

New Fannie Mae Forbearance Program for Military Families

Fannie Mae has announced plans to give military families a break on their mortgage payments if they are struggling because of the death or injury of a service member.

Fannie says its "Unique Hardship" guidelines allow the agency to reduce or suspend borrowers' monthly payments up to six months. In addition, they will suspend reporting to credit bureaus for up to six months to minimize the impact on the borrower's credit score.

The military has established a special phone number for injured military or surviving spouses to use if they are struggling with mortgage payments: 1-877-MIL-4566.

If you or a family member are currently serving in the military... first and foremost: Thank You!  Also, there may be other helps and assistance available to you - even if your loan is not backed by Fannie Mae.  Contact a Foreclosure Counselor through the MN Home Ownership Center TODAY to learn about your options if you are struggling with mortgage payments.  To find your local non-profit, FREE Foreclosure Counselor, click here.

Training Opportunities in Affordable Housing

Need CEU's?  Interested in Affordable Housing Issues?

As part of our goal of promoting and advancing successful home ownership in Minnesota, we periodically highlight training and continuing education opportunities for real estate and housing professionals. Today, we’d like to highlight three upcoming workshops/seminars:

1. 2010 Affordable Homes Congress
Attend the 2010 Affordable Homes Congress to get the answers and information you need to succeed in affordable housing today.
     When: October 14-15, 2010
     Where: Radisson Hotel and Conference Center Minneapolis
                 3131 Campus Drive, Plymouth, MN 55441
     More Info: Online information here
                           ** CEUs have been applied for**

 2. Homes for All 2010
Homes for All 2010 seeks to build a community platform to affirm the belief that all Minnesotans deserve a safe, affordable place to call home; connect resources and stakeholders; and create sustainable communities.
     When: November 8, 2010
     Where: St. Paul RiverCentre
     More Info: http://www.homes-for-all.org/index.html

3. Fourth Annual Emerging Markets Homeownership Initiative Summit
The EMHI Summit event is designed primarily for Realtors, lenders, non-profits, government, and others working in the homeownership arena. Hear a comprehensive analysis of the current status of emerging marketing homeownership in Minnesota; learn from panelists and speakers about opportunities and successes in serving emerging markets.
     When: December 8, 2010
     Where: U of MN Continuing Education and Conference Center
     More Info: http://hocmn.org/en/emhi-summit-2010.cfm
           ** CEUs have been applied for**

Monday, September 20, 2010

Foreclosures Are Getting Worse

As we've highlighted on this blog before (here and here, for example) Minnesota is NOT out of the woods yet, and will continue to see elevated numbers of foreclosures for quite a while.

On Friday, September 17th, Minnesota's most-populated county, Hennepin County, through its Taxpayer Services department, released a fresh round of information regarding Sheriff Sale data for August, 2010... and the data does not look good.

For the county, the number of foreclosure sales (Sheriff Sales) conducted in August of 2010 exceeded the number during the same periods during each of the three preceding years - 2009, 2008, and 2007.

Here is how August 2010 compares to the three previous years: 

(Click To Enlarge)


According to Hennepin County Taxpayer Services:

If foreclosure sales continue at this pace for the rest of the this year, the number may reach the 6,000-6,300 range

If this number is reached, 2010 could outpace 2009, and even rival the record-breaking number of 7,348 set in 2008.


In actuality, August 2010 recorded the 7th highest number of foreclosures in Hennepin County in a single month since these numbers have been tracked:


Minnesota homeowners continue to struggle with mortgage payments and continue to face the specter of foreclosure.  But it's not all doom-and-gloom.  Hennepin County (Taxpayer Services, Hennepin County Library and others) continues to work with the MN Home Ownership Center and its network of Housing Counseling agencies to offer FREE trustworthy resources to avoid foreclosure.  For a complete list of information sessions hosted by Hennepin County and the Minnesota Home Ownership Center, click here.

If you can't join us at one of the sessions, but would like to learn about what resources and assistance are available to Minnesota homeowners to avoid foreclosure, you can learn more about foreclosure avoidance services that are available - FREE - at the Center's website here or by calling us at 651-659-9336. 

Don't delay... the sooner you contact a non-profit housing counseling agency, the more options you have!

Friday, September 17, 2010

Fannie Mae's National Housing Survey

Fannie Mae has released the latests findings of their National Housing Survey that polled homeowners and renters between June 2010 and July 2010. These findings were compared to a similar survey released in April  (See the Center's April 22 blog post about that here). 

The Survey has some interesting facts and figures to digest:

Regarding purchasing a home:
  • 70% of Americans believe it’s a good time to buy a home - even with all of the issues we've been hearing about in the housing industry.  This number is up from 64% of respondents from the earlier survey conducted in January.
  • A large majority (78%) believe home prices have either bottomed or will rise over the next year, up from 73 percent in January.
Here's a great quote from the press release of the survey:
“Although most Americans believe that home prices have bottomed, they are adopting a much more cautious approach toward buying,” said Doug Duncan, Vice President and Chief Economist, Fannie Mae.

The Center believes that potential homebuyers should ALWAYS be cautious when buying their first home.  That's why we offer the state's premier homebuyer (pre-purchase) education curriculum, Home Stretch.  To learn more about Home Stretch, and other services for homebuyers, visit the Center's website here.

The survey has interesting information about CURRENT homeowners as well:
  • 22% of mortgage holders (homeowners) said that they have reduced their mortgage debt “significantly” over the past year, while 27 percent say they have reduced their non-mortgage debt significantly. (!!)
  • Nearly 20% of homeowners know someone who has strategically defaulted, or stopped making their mortgage payments even when they could afford to make them.
The survey also has interesting data about housing attitudes from minority groups including African Americans and Latinos. 

For more information about the survey and to see the complete report, visit Fannie Mae's website, here.  

Thursday, September 16, 2010

More Help For Struggling Homeowners

More help for local residents struggling to keep their homes is available in upcoming workshops sponsored by several non-profit and governmental partners.

FREE Foreclosure Prevention Workshops
at Hennepin County Libraries:


At these informal sessions, homeowners and renters, can learn about the foreclosure process, what kinds of helps and assistance are available in both in Minnesota and nationally, and even meet with non-profit housing counselors (foreclosure prevention specialists), representatives from Hennepin County Taxpayer Services, and, in some sessions, attorneys specializing in real estate services. In addition, attendees will be able to set up an appointment for a more personalized, in-depth discussion at a later time.

These workshops are a partnership of several organizations including the MN Home Ownership Center, PRG Inc., Hennepin County, Hennepin County Taxpayer Services, Hennepin County Library, Twin Cities Habitat for Humanity and others.

Upcoming workshops:


  • Thursday, Oct. 7th, 6:30-8:00pm  -  Maple Grove Library
             (Click On Library Name for Google Map)


To view these, and other events the Center has scheduled, click here.


Thursday, September 9, 2010

Subprime 2.0?

Edward Pinto, the Chief Credit Officer of Fannie Mae back in the 1980's, has written an Op-Ed for Bloomberg titled "Subprime 2.0 Is Coming Soon to a Suburb Near You" that talks about no-money down and lowered credit score requirements for government-backed loans.  [Fair warning: this op-ed is takes an EXTREMELY negative view of the loosened underwriting standards that became prevelant in the mid-2000's.]

One of the more interesting quotes in the article is where he cites the number of no-money down mortgages (or extremely low-money down) as a percentage of all loans:

In 1990, one in 200 home-purchase loans (all government insured) had a down payment of less than or equal to 3 percent. By 2003, one in seven home buyers had such a low down payment, and by 2006 about one in three put no money down.


Visually... this is what I've come up with:
 

Click to Enlarge


Now... Pinto believes we will to return to an environment of subprime lending that he refers to as “Subprime 2.0,” as the FHA continues to accept borrowers with low Fico scores and minimal down payments.

For example, the FHA’s average down payment is just 4 percent,” he wrote. “Even this meager amount disappears after adjusting for seller concessions and financed insurance premiums.

Pinto is calling for a return to hefty down payments - - a minimum of 20 percent down, with few exceptions, and believes documentation should be “iron-clad."

NOW, couple of questions for our readers (feel free to voice your opinion in the comments): 
  • What would this mean for those of us working on affordable housing issues? 
  • Would this cause more problems than it solves?
  • Are there other solutions to affordable housing... that don't involve simply lowering lending standards? 

One of the conferences that takes up the issue of affordable housing... and discusses related policy issues is the "Homes For All" Conference.  You can learn more about the conference here. 

Tuesday, August 31, 2010

Why Refi? Is it right for you?

According to a new article at MarketWatch based on CoreLogic data, more than a quarter of households that refinanced between January and June of 2010, chose a 15-year fixed-rate mortgage.  This compares to only 18.5% who chose that option in 2009, and is nearly three times the 9% that chose a 15-year refi in 2007.

Why is the 15-year refi becoming so popular?
  • One possible explanation is that interest rates on 15-year loans are now so low that borrowers can handle the larger mortgage payment.  If someone has a 6.5% 30-year mortgage on a $200,000 house, their monthly payment is about $1,270.  Refinancing to a 15-year fixed rate at about 4%, means a payment of about $1,480.  An extra couple hundred dollars a month and the loan is paid off over a DECADE earlier.
  • Could a second explanation be a change in our national psyche?  Is it possible that we as a nation are becoming more debt-averse?  Personal finance blogs and magazines are flourishing.  Recent reports show that we owe less on our credit cards and we're even paying off our car loans.  Hmm...  Your thoughts are welcome in the comments.

Now... paying off debt is a GREAT THING.  And refinancing from a 30-year to a 15-year loan can save a tremendous amount of money in interest payments over the coming years... but refinancing can also be dangerous!  The MN Home Ownership Center oversees a network of Refinance Counselors* (Housing Counselors) that provide home owners with an opportunity to compare a current mortgage against a potential refinanced mortgage or second mortgage. Counselors take time to compare the terms with you, and to tell you what those changes will mean for your monthly finances - in real terms - without trying to sell you ANYTHING.
 
For more information about Refinance Counseling in Minnesota - or if you're thinking about refinancing your mortgage - visit the MN Home Ownership Center's website, here.
 
 
* Minnesota law requires you obtain a certificate from a qualified "Refinance Counselor" before you refinance your loan if you have a "special mortgage" - a loan from a state, local or tribal government or nonprofit organization with payments that vary with income, zero or deferred interest or other unique conditions, and is highly recommended for ANYONE thinking about refinancing their mortgage.  A small fee for this service may apply.

Monday, August 30, 2010

Taking On Time Magazine

In the world of blogging, there's a traffic-generating trick known as 'punching upward' (or fighting upward, punching above your weight class, etc.) - in which a blog picks a fight with a highly trafficked blog or media source, in order to gather some of that blog's traffic in the ensuing battle.  While this is certainly not the primary goal of this post - we won't complain if we see an uptick in traffic as we take on Time Magazine and their most-recent cover story "Rethinking Homeownership, why owning a home may no longer make economic sense."

The actual title of the article is even more menacing "The Case Against Homeownership". 


Homeownership has been proven, over and over, to be the NUMBER ONE driver of wealth creation for low- to moderate- income homebuyers over time.  (The key being over TIME).  Even Barbara Kiviat, the article's author, understands this fact:

Homeownership has done plenty of good over the decades; it has provided stability to tens of millions of families and anchored a labor-intensive sector of the economy.

The article... which is only available in an abridged version online states that:

But the dark side of homeownership is now all too apparent: foreclosures and walkaways, neighborhoods plagued by abandoned properties and plummeting home values, a nation in which families have $6 trillion less in housing wealth than they did just three years ago.


The problem has never been - and never will be - homeownership. 

The problem stems from one of preparation, education and expectations.  BEFORE deciding to purchase, homebuyers need to fully understand the financial implications, the risks and the responsibilities of homeownership - and the information needs to come from an unbiased source... not a marketing/sales pitch from someone who has a financial stake in the decisions the homebuyer makes.  Homeownership should never be seen as a short-term vehicle to wealth creation.

In Minnesota, THE source of unbiased information about the home buying process and homeownership is HOME STRETCH.  A Home Stretch Workshop will help you become an informed, prepared consumer. The workshop offers objective, practical information to help you:

  • Determine your REAL financial situation
  • Understand credit, credit issues, and how credit affects the costs of homeownership
  • Decide what type of mortgage is best for your needs
  • Select the right home for your family
  • Understand the loan closing process
  • Find special programs just for first-time homebuyers

And, even though we are the HOMEOWNERSHIP CENTER... we consider it a success if someone takes a HomeStretch workshop, or speaks with a pre-purchase counselor, and decides that homeownership is not right for them.  Homeownership is NOT right for everyone... and being a successful homeowner isn't easy.

To find out more, visit the MN Home Ownership Center's website, here.

Tuesday, August 24, 2010

Census Bureau Releases Housing Data

This is actually a couple of days old... but I thought our readers might be interested in knowing that the U.S. Census Bureau has released the 2009 American Housing Survey, The Report covers statistics about apartments, single-family homes, manufactured housing, new construction and vacant housing units throughout the country.

According to the new survey... the nation's homeowners paid a median of $1,000 in monthly housing costs in 2009, compared with $808 for renters. However, renters usually paid a higher percentage of their household income on these costs than did owners (31 percent compared with 20 percent).

A wide range of specific topics is covered in the survey, such as the presence of air conditioning, crowding, housing costs, special living services offered to older residents, type of heating fuel used, cost of utilities and size of the home... and even 'subjective' information like satisfaction with the neighborhood. Of course, the survey also covers the demographic characteristics of the housing units' occupants.

Here are some interesting facts from the report:
  • Thirty-two percent of owner-occupied units were owned free and clear,
  • 66 percent had a regular and/or home equity mortgage and 2 percent had only a line-of-credit.
  • The most important consideration for recent movers in choosing their homes was financial (28 percent), followed by room layout/design (15 percent) and size of home (10 percent). Furthermore, the most common reasons recent movers had for choosing their neighborhoods were convenience to job (20 percent), convenience to friends or relatives (14 percent), look/design of neighborhood (10 percent) and the house itself (10 percent).
  • Ten percent of communities had secured entrances, with the likelihood somewhat higher (15 percent) in new communities. [Ed... Really? 10% of all single-family homes are in gated communities??]

Data from this survey (In MS Excel format) are available at the national and regional level, and for inside and outside metropolitan statistical areas, and urban and rural areas.

Remember... The Minnesota Homeownership Center’s goal is SUCCESSFUL homeownership. If you’re thinking of buying your first home… the Center is here to help. Workshops for first-time buyers are available throughout the state and counselors (one-on-one meetings) are also available. If you’d like to learn more, visit our website here.