Thursday, October 21, 2010

What A Difference A Decade Makes

I recently came accross a report from the Federal Reserve Bank of San Fransisco entitled "Underwater Mortgages" where the authors,  John Krainer and Stephen LeRoy, attempt to determine the point at which underwater borrowers decide to throw in the towel and walk away from their homes.

While the article has some interesting information about the 'boiling point', I found that two of the images that accompany the report are just as interesting for people working in housing in Minnesota.

The first image shows the share of underwater mortgages in the fourth quarter of 2000:


(Click To Enlarge)

According to the figure, in the fourth quarter of 2000, Minnesota was one of only a dozen states where the share of 'underwater' mortgages was less than one tenth of one percent! (between 0% and 0.1%).


However, by fourth quarter 2009, our rate of negative equity homeowners had increased to between 6% and 10%:


(Click To Enlarge)

Interestingly... NO STATE was in the 0%-0.1% category by the end of the 'aughts'.

The complete report is here.

Tuesday, October 19, 2010

Residential Foreclosures in Minnesota Report

Minnesota Housing has just released the Summer 2010 version of its "Residential Foreclosures in Minnesota" report, based on delinquency and foreclosure information from EVERY Zip Code in the state (through June 2010)... and there is a ton of great information for real estate and lending professionals, municipalities and elected officials and others that are working on foreclosure prevention and remediation efforts.

The report is available online here.

Here are just a handful of the highlights of the report:
  • Although the number of sheriff sales in Minnesota dropped from 26,000 to 23,000 between 2008 and 2009, the 2009 level is dramatically higher than the 6,500 sales that occurred in 2005.2 In addition, the number of sheriff sales started to increase again in late 2009 and early 2010.3 Sheriff sales are expected to rise back up to the 26,000 level in 2010.
  • Between 2007 and 2010, the subprime market’s share of residential mortgages in foreclosure dropped from 54% to 25% in Minnesota.  During the same period, the prime market’s share increased from 40% to 60%.
  • There is concern about alt-A loans and option ARMs that will reset or recast in the next few years.

The report is full of great graphics that show exactly where the highest concentrations of delinquencies (60-day lates) and foreclosures are happening.  Here is the map of loans that are 60-days or more delinquent throughout the state of Minnesota:


(Click To Enlarge)


From this map alone... it is clear that the foreclosure crisis is continuing to move out of the core cities of Minneapolis and St. Paul, and into the outer ring communities just outside the seven-county metropolitan area, particularly in Wright, Sherburne, and Isanti counties.

The report also maps the prevalence of REO properties and homes in foreclosure (as of June, 2010).  In addition... the data is not just available in map form, but Minnesota Housing has included the information for EVERY Zip Code (where there are more than 200 residential parcels). 

Go ahead... go dig through the report... let us know if you find anything that surprises you.  Your comments are welcome!

Friday, October 8, 2010

Bank of America Halts Foreclosures in Minnesota

According to a press release on the Bank of America website, BoA has halted ALL foreclosure sales in all 50 states.  This, obviously, includes Minnesota.

The actual text of the press release is:
Bank of America has extended our review of foreclosure documents to all fifty states. We will stop foreclosure sales until our assessment has been satisfactorily completed. Our ongoing assessment shows the basis for our past foreclosure decisions is accurate. We continue to serve the interests of our customers, investors and communities. Providing solutions for distressed homeowners remains our primary focus.

The wording of their press release is interesting.  It states that they will halt "foreclosure sales" until they've finalized their internal reviews... but it does not state anything about the REST of the foreclosure process.  Will they continue all the steps PRIOR to the Sheriff's sale in Minnesota?  (For an overview of the steps, view our Foreclosure Process Infographic). 

Will other lenders follow suit?  Let us know what you think in the comments.

We will continue to monitor the situation... and let our readers know of updates as they become available.

Struggling homeowners should be aware that this decision by Bank of America will NOT, ultimately, end their financial crisis.  If you are struggling with payments - whether you are a Bank of America client or not, the best resource in Minnesota the MN Home Ownership Center's network of FREE Foreclosure Counselors.  These counselors can work with you to find individualized solutions to YOUR personal mortgage crisis and answer questions about how foreclosure related policies and programs affect you.  To find your closest counselor, click here.


UPDATE: We've received information from Bank of America... that specifically states that the ONLY part of the process that is halted is the actual sale date... and ONLY those sale dates that fall between October 9, 2010 and November 1, 2010:
First, I want to clarify that there is no moratorium in place. What we have done is postpone any scheduled foreclosure sales, that fall between 10/9 and 11/1 to a date after November 1st. This is to allow for additional time to complete necessary document reviews. All other foreclosure activity will continue as usual.

Thursday, October 7, 2010

Housing Counselor Training Opportunity

Homebuyer Counseling Training and Certification

The Minnesota Home Ownership Center is offering homebuyer counseling training and certification for housing professionals that provide pre-purchase counseling in Minnesota. This training will also help Real Estate agents that work with first-time homebuyers by sharing techniques, methods and practices to resolving any barriers that first-time buyers may have to homeownership.

Activities include determining mortgage readiness, prequalification, reviewing credit reports and many other key counseling/home buying components.

Participants interested in Continuing Education credits can pursue these through the "Self-Directed" option (Individual Continuin Ed Course Approval) through the MN Dept. of Commerce.  

Participants interested in obtaining certification must complete the training and pass the in-class exam.

For additional information or to register, click here.

Monday, October 4, 2010

Can lender access property after foreclosure sale?

This post is a guest post by attorney Jeffrey O'Brien, partner with Mansfield Tanick & Cohen, P.A. who specializes  in the areas of business and corporate law, real estate law, estate and business succession planning and probate law.

___________________________

Can a Foreclosing Lender Enter a Property
During the Redemption Period?

In Minnesota, foreclosures work a bit differently than other states. Not only does Minnesota have a non-judicial foreclosure process (unlike most states which only allow foreclosures to be brought by court action), but Minnesota is also one of only ten (10) states that provides for post-sale redemption rights.

The most significant implication of a foreclosed homeowner having post-sale redemption rights (as opposed to pre-sale redemption rights) is that the foreclosure sale does not end the process. In a way, it is only the beginning. For the next six (6) months, Minnesota law allows the homeowner to stay in possession of the property, with the understanding that up until the end of the six (6) months, the homeowner could, theoretically, pay off the foreclosing lender’s mortgage plus the costs of the foreclosure and regain ownership of the property.

This post-sale redemption period can be tricky, for a number of reasons. For example, the lender is not able to list the property for sale, based upon the fact that the homeowner can redeem the property during that period, and allowing the lender to sell the property to someone else would create a significant ownership dispute, not to mention the fact that there would seem to be little to no market for purchasing a property that could be redeemed at less than the new buyer’s purchase price for a period of time. For this reason, if the homeowner abandons the property, the lender has the option to seek a court-ordered shortening of the redemption period to five weeks.

Even if the redemption period is not shortened, the lender is not powerless to protect its property. That’s because Minnesota Statutes Section 582.031 allows the lender, in certain circumstances, to enter the property during the redemption period and take steps to protect the property. The statute provides that “if premises described in a mortgage or sheriff's certificate are vacant or unoccupied, the holder of the mortgage or sheriff's certificate or the holder's agents and contractors may, but is under no obligation to, enter upon the premises to protect the premises from waste, until the holder of the mortgage or sheriff's certificate receives notice that the premises are occupied.”

Subdivision 2 of the statute goes on to clarify what actions the lender may take to protect the premises from waste: “install or change locks on doors and windows, board windows, install an alarm system, provide a resident caretaker, and otherwise prevent or minimize damage to the premises from the elements, vandalism, trespass, or other illegal activities.” For example, given Minnesota’s harsh winters, a lender may take steps to ensure that pipes don’t freeze and burst by winterizing the property.

In order to protect the homeowner’s redemption rights (which include the right of possession of the property until the expiration of the owner’s redemption period), if the holder of the mortgage or sheriff's certificate installs or changes locks, a key to the premises must be promptly delivered to the homeowner or any person lawfully claiming through the mortgagor, upon request.

Section 582.031 is a necessary result of Minnesota’s post-sale redemption rights, and lenders should be aware of their rights during the redemption period just as much as they need to be concerned about the homeowner’s rights.
___________________________

This post was originally published on Jeff's blog: here. 
Reposted with permission.

For more information about your rights after a foreclosure sale - during Minnesota's Redemption Period - the Center has created a Redemption Period Fact Sheet, or you can visit the Center's website here.

HECAT Funding Awards Announced

The State of Minnesota is unique in that we are the only state in the country with a dedicated pool of funds that provides financial support to eligible non-profit organizations to deliver a variety of homebuyer/homeowner education, counseling and training services to Minnesotans. This dedicated pool is known as HECAT (The Homeownership Education, Counseling and Training Fund).

Some of the valuable services that are funded through HECAT include:
  • Pre-purchase education and counseling (Home Stretch),
  • Post-purchase education and counseling,
  • Home equity conversion counseling (Reverse Mortgages) and
  • Foreclosure counseling
Funds for HECAT come from four funding partners that are fully invested in ensuring that Minnesotans have access to the education and counseling tools necessary to achieve successful home ownership:
Each of the four funding partners not only contribute financial resources they also actively participate in the grant-making process.

Additional information about HECAT can be found here.

A complete list of organizations that have been granted HECAT funds for the 2010-2011 program year is available here. (PDF Document)


Friday, October 1, 2010

Open Position - Dakota County CDA

Interested in helping people begin or maintain sucessful homeownership?  Looking for a new career? 

The Dakota County Community Development Agency is seeking an experienced Homeownership professional to provide housing counseling services in the area of pre-purchase and mortgage default and foreclosure prevention. 

Duties include:  Conduct homebuyer education sessions; perform foreclosure program intake; conduct applicant interviews, determine eligibility, provide counseling services, respond to inquiries, and maintain records. 

Starting salary:  $3,284 - $3,542/mo. DOQ, plus benefits. 

This position is grant-funded through September 30, 2011 with future employment dependent on continued program funding.  Some evening and weekend hours may be required.  Requires 4 years related education and/or experience; Certified Mortgage Foreclosure Prevention Specialist preferred.  

Completed CDA application forms must be received in the CDA office by 4:30pm on October 20, 2010.  You can use their online application process here: www.dakotacda.org, or call their Jobs Line at (651) 675-4441.  The Dakota County CDA is an Equal Opportunity Employer

Thursday, September 30, 2010

Foreclosure Suspensions in Minnesota?

UDPATE:  Bank of America & PNC have halted foreclosures in ALL 50 states, including Minnesota.  If other lenders join them, we'll update this blog post.


Recently a number of stories have hit the media regarding certain servicers halting or suspending foreclosures due to issues (errors) with their internal document processing and legal procedures.  The servicing companies that have voluntarily issued moratoria are GMAC and JPMorgan Chase, although many other servicers are reviewing their procedures, and others may follow suit.


The question has arisen as to whether these foreclosure suspensions/moratoria will affect any Minnesota homeowners.  The short answer is: probably not.


The key reason is due to the fact that the vast majority of foreclosures in Minnesota follow a process known as Foreclosure by Advertisement, and not the process of judicial foreclosure (where a judge must enter a judgment of foreclosure against a homeowner before the house can be auctioned/sold).  In Minnesota, no such step is required if the servicer is pursuing Foreclosure by Advertisement.


For more information about the Foreclosure by Advertisement process, the MN Home Ownership Center has created a fact sheet that highlights the steps a lien holder must take to foreclose.  That document is here.


From the NY Times:
The lender, JPMorgan Chase, said on Wednesday that it was halting 56,000 foreclosures because some of its employees might have improperly prepared the necessary documents. All of the suspensions are in the 23 states where foreclosures must be approved by a court, including New York, New Jersey, Connecticut, Florida and Illinois.  [Emphasis ours]


The Center will continue to monitor the situation, and if other servicers join the ranks of GMAC and JPMorgan Chase, we'll update the blog.  In addition... if any servicers halt foreclosures in Minnesota, we'll highlight that information as well.


If you're struggling with your mortgage payments - no matter who your lender or servicer is - getting help as soon as possible is key.  There is a network of FREE, non-biased, non-profit Housing Counselors that specialize in foreclosure prevention.  To locate your closest counselor, visit the MN Home Ownership Center's website, here.

Monday, September 27, 2010

New Fannie Mae Forbearance Program for Military Families

Fannie Mae has announced plans to give military families a break on their mortgage payments if they are struggling because of the death or injury of a service member.

Fannie says its "Unique Hardship" guidelines allow the agency to reduce or suspend borrowers' monthly payments up to six months. In addition, they will suspend reporting to credit bureaus for up to six months to minimize the impact on the borrower's credit score.

The military has established a special phone number for injured military or surviving spouses to use if they are struggling with mortgage payments: 1-877-MIL-4566.

If you or a family member are currently serving in the military... first and foremost: Thank You!  Also, there may be other helps and assistance available to you - even if your loan is not backed by Fannie Mae.  Contact a Foreclosure Counselor through the MN Home Ownership Center TODAY to learn about your options if you are struggling with mortgage payments.  To find your local non-profit, FREE Foreclosure Counselor, click here.

Training Opportunities in Affordable Housing

Need CEU's?  Interested in Affordable Housing Issues?

As part of our goal of promoting and advancing successful home ownership in Minnesota, we periodically highlight training and continuing education opportunities for real estate and housing professionals. Today, we’d like to highlight three upcoming workshops/seminars:

1. 2010 Affordable Homes Congress
Attend the 2010 Affordable Homes Congress to get the answers and information you need to succeed in affordable housing today.
     When: October 14-15, 2010
     Where: Radisson Hotel and Conference Center Minneapolis
                 3131 Campus Drive, Plymouth, MN 55441
     More Info: Online information here
                           ** CEUs have been applied for**

 2. Homes for All 2010
Homes for All 2010 seeks to build a community platform to affirm the belief that all Minnesotans deserve a safe, affordable place to call home; connect resources and stakeholders; and create sustainable communities.
     When: November 8, 2010
     Where: St. Paul RiverCentre
     More Info: http://www.homes-for-all.org/index.html

3. Fourth Annual Emerging Markets Homeownership Initiative Summit
The EMHI Summit event is designed primarily for Realtors, lenders, non-profits, government, and others working in the homeownership arena. Hear a comprehensive analysis of the current status of emerging marketing homeownership in Minnesota; learn from panelists and speakers about opportunities and successes in serving emerging markets.
     When: December 8, 2010
     Where: U of MN Continuing Education and Conference Center
     More Info: http://hocmn.org/en/emhi-summit-2010.cfm
           ** CEUs have been applied for**

Monday, September 20, 2010

Foreclosures Are Getting Worse

As we've highlighted on this blog before (here and here, for example) Minnesota is NOT out of the woods yet, and will continue to see elevated numbers of foreclosures for quite a while.

On Friday, September 17th, Minnesota's most-populated county, Hennepin County, through its Taxpayer Services department, released a fresh round of information regarding Sheriff Sale data for August, 2010... and the data does not look good.

For the county, the number of foreclosure sales (Sheriff Sales) conducted in August of 2010 exceeded the number during the same periods during each of the three preceding years - 2009, 2008, and 2007.

Here is how August 2010 compares to the three previous years: 

(Click To Enlarge)


According to Hennepin County Taxpayer Services:

If foreclosure sales continue at this pace for the rest of the this year, the number may reach the 6,000-6,300 range

If this number is reached, 2010 could outpace 2009, and even rival the record-breaking number of 7,348 set in 2008.


In actuality, August 2010 recorded the 7th highest number of foreclosures in Hennepin County in a single month since these numbers have been tracked:


Minnesota homeowners continue to struggle with mortgage payments and continue to face the specter of foreclosure.  But it's not all doom-and-gloom.  Hennepin County (Taxpayer Services, Hennepin County Library and others) continues to work with the MN Home Ownership Center and its network of Housing Counseling agencies to offer FREE trustworthy resources to avoid foreclosure.  For a complete list of information sessions hosted by Hennepin County and the Minnesota Home Ownership Center, click here.

If you can't join us at one of the sessions, but would like to learn about what resources and assistance are available to Minnesota homeowners to avoid foreclosure, you can learn more about foreclosure avoidance services that are available - FREE - at the Center's website here or by calling us at 651-659-9336. 

Don't delay... the sooner you contact a non-profit housing counseling agency, the more options you have!

Friday, September 17, 2010

Fannie Mae's National Housing Survey

Fannie Mae has released the latests findings of their National Housing Survey that polled homeowners and renters between June 2010 and July 2010. These findings were compared to a similar survey released in April  (See the Center's April 22 blog post about that here). 

The Survey has some interesting facts and figures to digest:

Regarding purchasing a home:
  • 70% of Americans believe it’s a good time to buy a home - even with all of the issues we've been hearing about in the housing industry.  This number is up from 64% of respondents from the earlier survey conducted in January.
  • A large majority (78%) believe home prices have either bottomed or will rise over the next year, up from 73 percent in January.
Here's a great quote from the press release of the survey:
“Although most Americans believe that home prices have bottomed, they are adopting a much more cautious approach toward buying,” said Doug Duncan, Vice President and Chief Economist, Fannie Mae.

The Center believes that potential homebuyers should ALWAYS be cautious when buying their first home.  That's why we offer the state's premier homebuyer (pre-purchase) education curriculum, Home Stretch.  To learn more about Home Stretch, and other services for homebuyers, visit the Center's website here.

The survey has interesting information about CURRENT homeowners as well:
  • 22% of mortgage holders (homeowners) said that they have reduced their mortgage debt “significantly” over the past year, while 27 percent say they have reduced their non-mortgage debt significantly. (!!)
  • Nearly 20% of homeowners know someone who has strategically defaulted, or stopped making their mortgage payments even when they could afford to make them.
The survey also has interesting data about housing attitudes from minority groups including African Americans and Latinos. 

For more information about the survey and to see the complete report, visit Fannie Mae's website, here.  

Thursday, September 16, 2010

More Help For Struggling Homeowners

More help for local residents struggling to keep their homes is available in upcoming workshops sponsored by several non-profit and governmental partners.

FREE Foreclosure Prevention Workshops
at Hennepin County Libraries:


At these informal sessions, homeowners and renters, can learn about the foreclosure process, what kinds of helps and assistance are available in both in Minnesota and nationally, and even meet with non-profit housing counselors (foreclosure prevention specialists), representatives from Hennepin County Taxpayer Services, and, in some sessions, attorneys specializing in real estate services. In addition, attendees will be able to set up an appointment for a more personalized, in-depth discussion at a later time.

These workshops are a partnership of several organizations including the MN Home Ownership Center, PRG Inc., Hennepin County, Hennepin County Taxpayer Services, Hennepin County Library, Twin Cities Habitat for Humanity and others.

Upcoming workshops:


  • Thursday, Oct. 7th, 6:30-8:00pm  -  Maple Grove Library
             (Click On Library Name for Google Map)


To view these, and other events the Center has scheduled, click here.


Thursday, September 9, 2010

Subprime 2.0?

Edward Pinto, the Chief Credit Officer of Fannie Mae back in the 1980's, has written an Op-Ed for Bloomberg titled "Subprime 2.0 Is Coming Soon to a Suburb Near You" that talks about no-money down and lowered credit score requirements for government-backed loans.  [Fair warning: this op-ed is takes an EXTREMELY negative view of the loosened underwriting standards that became prevelant in the mid-2000's.]

One of the more interesting quotes in the article is where he cites the number of no-money down mortgages (or extremely low-money down) as a percentage of all loans:

In 1990, one in 200 home-purchase loans (all government insured) had a down payment of less than or equal to 3 percent. By 2003, one in seven home buyers had such a low down payment, and by 2006 about one in three put no money down.


Visually... this is what I've come up with:
 

Click to Enlarge


Now... Pinto believes we will to return to an environment of subprime lending that he refers to as “Subprime 2.0,” as the FHA continues to accept borrowers with low Fico scores and minimal down payments.

For example, the FHA’s average down payment is just 4 percent,” he wrote. “Even this meager amount disappears after adjusting for seller concessions and financed insurance premiums.

Pinto is calling for a return to hefty down payments - - a minimum of 20 percent down, with few exceptions, and believes documentation should be “iron-clad."

NOW, couple of questions for our readers (feel free to voice your opinion in the comments): 
  • What would this mean for those of us working on affordable housing issues? 
  • Would this cause more problems than it solves?
  • Are there other solutions to affordable housing... that don't involve simply lowering lending standards? 

One of the conferences that takes up the issue of affordable housing... and discusses related policy issues is the "Homes For All" Conference.  You can learn more about the conference here. 

Tuesday, August 31, 2010

Why Refi? Is it right for you?

According to a new article at MarketWatch based on CoreLogic data, more than a quarter of households that refinanced between January and June of 2010, chose a 15-year fixed-rate mortgage.  This compares to only 18.5% who chose that option in 2009, and is nearly three times the 9% that chose a 15-year refi in 2007.

Why is the 15-year refi becoming so popular?
  • One possible explanation is that interest rates on 15-year loans are now so low that borrowers can handle the larger mortgage payment.  If someone has a 6.5% 30-year mortgage on a $200,000 house, their monthly payment is about $1,270.  Refinancing to a 15-year fixed rate at about 4%, means a payment of about $1,480.  An extra couple hundred dollars a month and the loan is paid off over a DECADE earlier.
  • Could a second explanation be a change in our national psyche?  Is it possible that we as a nation are becoming more debt-averse?  Personal finance blogs and magazines are flourishing.  Recent reports show that we owe less on our credit cards and we're even paying off our car loans.  Hmm...  Your thoughts are welcome in the comments.

Now... paying off debt is a GREAT THING.  And refinancing from a 30-year to a 15-year loan can save a tremendous amount of money in interest payments over the coming years... but refinancing can also be dangerous!  The MN Home Ownership Center oversees a network of Refinance Counselors* (Housing Counselors) that provide home owners with an opportunity to compare a current mortgage against a potential refinanced mortgage or second mortgage. Counselors take time to compare the terms with you, and to tell you what those changes will mean for your monthly finances - in real terms - without trying to sell you ANYTHING.
 
For more information about Refinance Counseling in Minnesota - or if you're thinking about refinancing your mortgage - visit the MN Home Ownership Center's website, here.
 
 
* Minnesota law requires you obtain a certificate from a qualified "Refinance Counselor" before you refinance your loan if you have a "special mortgage" - a loan from a state, local or tribal government or nonprofit organization with payments that vary with income, zero or deferred interest or other unique conditions, and is highly recommended for ANYONE thinking about refinancing their mortgage.  A small fee for this service may apply.

Monday, August 30, 2010

Taking On Time Magazine

In the world of blogging, there's a traffic-generating trick known as 'punching upward' (or fighting upward, punching above your weight class, etc.) - in which a blog picks a fight with a highly trafficked blog or media source, in order to gather some of that blog's traffic in the ensuing battle.  While this is certainly not the primary goal of this post - we won't complain if we see an uptick in traffic as we take on Time Magazine and their most-recent cover story "Rethinking Homeownership, why owning a home may no longer make economic sense."

The actual title of the article is even more menacing "The Case Against Homeownership". 


Homeownership has been proven, over and over, to be the NUMBER ONE driver of wealth creation for low- to moderate- income homebuyers over time.  (The key being over TIME).  Even Barbara Kiviat, the article's author, understands this fact:

Homeownership has done plenty of good over the decades; it has provided stability to tens of millions of families and anchored a labor-intensive sector of the economy.

The article... which is only available in an abridged version online states that:

But the dark side of homeownership is now all too apparent: foreclosures and walkaways, neighborhoods plagued by abandoned properties and plummeting home values, a nation in which families have $6 trillion less in housing wealth than they did just three years ago.


The problem has never been - and never will be - homeownership. 

The problem stems from one of preparation, education and expectations.  BEFORE deciding to purchase, homebuyers need to fully understand the financial implications, the risks and the responsibilities of homeownership - and the information needs to come from an unbiased source... not a marketing/sales pitch from someone who has a financial stake in the decisions the homebuyer makes.  Homeownership should never be seen as a short-term vehicle to wealth creation.

In Minnesota, THE source of unbiased information about the home buying process and homeownership is HOME STRETCH.  A Home Stretch Workshop will help you become an informed, prepared consumer. The workshop offers objective, practical information to help you:

  • Determine your REAL financial situation
  • Understand credit, credit issues, and how credit affects the costs of homeownership
  • Decide what type of mortgage is best for your needs
  • Select the right home for your family
  • Understand the loan closing process
  • Find special programs just for first-time homebuyers

And, even though we are the HOMEOWNERSHIP CENTER... we consider it a success if someone takes a HomeStretch workshop, or speaks with a pre-purchase counselor, and decides that homeownership is not right for them.  Homeownership is NOT right for everyone... and being a successful homeowner isn't easy.

To find out more, visit the MN Home Ownership Center's website, here.

Tuesday, August 24, 2010

Census Bureau Releases Housing Data

This is actually a couple of days old... but I thought our readers might be interested in knowing that the U.S. Census Bureau has released the 2009 American Housing Survey, The Report covers statistics about apartments, single-family homes, manufactured housing, new construction and vacant housing units throughout the country.

According to the new survey... the nation's homeowners paid a median of $1,000 in monthly housing costs in 2009, compared with $808 for renters. However, renters usually paid a higher percentage of their household income on these costs than did owners (31 percent compared with 20 percent).

A wide range of specific topics is covered in the survey, such as the presence of air conditioning, crowding, housing costs, special living services offered to older residents, type of heating fuel used, cost of utilities and size of the home... and even 'subjective' information like satisfaction with the neighborhood. Of course, the survey also covers the demographic characteristics of the housing units' occupants.

Here are some interesting facts from the report:
  • Thirty-two percent of owner-occupied units were owned free and clear,
  • 66 percent had a regular and/or home equity mortgage and 2 percent had only a line-of-credit.
  • The most important consideration for recent movers in choosing their homes was financial (28 percent), followed by room layout/design (15 percent) and size of home (10 percent). Furthermore, the most common reasons recent movers had for choosing their neighborhoods were convenience to job (20 percent), convenience to friends or relatives (14 percent), look/design of neighborhood (10 percent) and the house itself (10 percent).
  • Ten percent of communities had secured entrances, with the likelihood somewhat higher (15 percent) in new communities. [Ed... Really? 10% of all single-family homes are in gated communities??]

Data from this survey (In MS Excel format) are available at the national and regional level, and for inside and outside metropolitan statistical areas, and urban and rural areas.

Remember... The Minnesota Homeownership Center’s goal is SUCCESSFUL homeownership. If you’re thinking of buying your first home… the Center is here to help. Workshops for first-time buyers are available throughout the state and counselors (one-on-one meetings) are also available. If you’d like to learn more, visit our website here.

Wednesday, August 18, 2010

New Survey Shows Loan Mod Problems

A new consumer survey of households accross the country that have received, or tried to receive, a loan modification from their bank or servicer shows that banks routinely make errors or blatently break the rules established by the federal Making Home Affordable program.

The survey, by ProPublica, gives empirical evidence to what many of the MN Home Ownership Center's network of Foreclosure Counselors have been hearing for the past year: trying to work with servicers to obtain a loan modification can be an EXTREMELY frustrating undertaking.

Here are some of the results from the survey:
  • On average, homeowners had been seeking a modification for more than 14 months.
  • Homeowners seeking modifications reported having to send the same documents nearly six times on average.
  • 175 homeowners say they were advised, incorrectly, to fall behind on their mortgage in order to qualify for a modification.
  • Nearly half of the homeowners reported spending more than 10 hours per month (collecting documents, waiting on the phone, etc.). Most said they call, fax or mail once a week or more.
Most frustrating for those surveyed was that many times the servicers themselves made mistakes that resulted in a denial, and many times homeowners found the reason for denial unclear.


If you've thought about seeking a loan modification with your lender, there are ways to simplify  the process (although it's NEVER easy) and you want to be EXTREMELY careful that any modification they offer is really in your LONG-TERM best interest. The Center's network of Foreclosure Counselors are ready, willing and able to work with you on applying for a modification and help you decide if it will work for you.  In addition... there may be other ways to avoid foreclosure too.  Your counselor can help.

ALSO... we couldn't post about loan modifications without warning Minnesota Home Owners AGAIN, to make sure that they DO NOT PAY for any third-party loan modification service. Deal directly with your lender yourself, or with one of our free, non-profit Foreclosure Counselors. For additional information about preventing foreclosure in Minnesota, click here.


Monday, August 16, 2010

New Foreclosure Rescue Scam

Helping to keep struggling homeowners safe from scam artists and fraudsters is a lot like the carnival game "whack-a-mole".  Now that there are tough federal and state law enforcement actions that have begun to crack down on “foreclosure rescue” and “loan modification” scams, the vultures/moles have "popped up" with a new fraud: "Forensic Loan Audits."

According to a recent "Consumer Alert" from the Federal Trade Commission, this latest fraud follows this pattern: In exchange for an upfront fee (ranging from a few hundred to a few thousand dollars), so-called 'forensic loan auditors' offer to review the homeowner’s mortgage loan documents to determine whether the lender complied with state and federal mortgage lending laws. If a violation is found, the “auditors” say their findings can be used to avoid foreclosure, accelerate the loan modification process, reduce the loan principal, or even cancel the loan.

NOT TRUE!  The FTC says that EVEN if these auditors find something wrong... it won't help with a loan modification or to avoid foreclosure.  Here's the information from their press release:

  • there is no evidence that forensic loan audits will help you get a loan modification or any other foreclosure relief, even if they’re conducted by a licensed, legitimate and trained auditor, mortgage professional or lawyer.
  • some federal laws allow you to sue your lender based on errors in your loan documents. But even if you sue and win, your lender is not required to modify your loan simply to make your payments more affordable.
  • if you cancel your loan, you will have to return the borrowed money, which may result in you losing your home.

The Minnesota Home Ownership Center is working with dozens of national, state and local partners through its "Look Before You Leap" campaign to help struggling homeowners to spot loan modification scams, find trusted help and report illegal activity to authorities.  DON'T FALL FOR A "LOAN AUDIT" SCAM!  You can learn more about the "Look Before You Leap" campaign on our Facebook Page and our website.
 
If you, or someone you know is struggling with mortgage payments... BE CAREFUL and don't wait until it's too late. To find your local non-profit, FREE Foreclosure Counselor, click here. For additional information about preventing foreclosure in Minnesota, click here.

Thursday, August 12, 2010

Foreclosures Rise Again - New Report

A report published this week by the Minnesota Home Ownership Center shows there were 13,093 foreclosures in Minnesota at the end of the second quarter, compared to 11,089 during the same period last year. If this pace continues, Minnesota will see a 13% increase in the number of foreclosures over 2009.

Even scarier... we could even rival the number of foreclosures seen in 2008, the highest number on record. In 2008 there were 26,251 foreclosures in the state.

The report is titled “2010 Semi-Annual Foreclosures in Minnesota: A Report Based on County Sheriff’s Sale Data.” It analyzes sheriff’s sale data, the foremost means of identifying foreclosures, from all Minnesota counties.

The report gives a county-by-county breakdown of foreclosures.  There are several counties that have experienced a HUGE increase in the number of foreclosures (comparing first-half 2010 to first-half 2009).  For example:
  • Goodhue County . . . . . . . . 137.8 % Increase
  • Kandiyohi County . . . . . . . . 128 % Increase
  • St. Louis County . . . . . . . . 76% Increase
  • Sherburne County . . . . . . . . 34 % Increase

Even the metro area counties have continued to see a year-over-year increase (although not as dramatic as parts of Greater MN):
  • Chisago County . . . . . . . . 28.2% Increase
  • Dakota County . . . . . . . . 25.2% Increase
  • Hennepin County . . . . . . . . 13.2% Increase
  • Ramsey County . . . . . . . . 5.6% Increase

While the numbers remain elevated... the Center remains committed to helping MN homeowners through its foreclosure counseling network!!  Remember... the sooner you or your clients seek help to avoid foreclosure, the more options they have available. If you, or someone you know is struggling with mortgage payments... don't wait (and don't EVER pay for help). To find your local non-profit, FREE Foreclosure Counselor, click here. For additional information about preventing foreclosure in Minnesota, click here.

Monday, August 9, 2010

New Fact Sheets for Homeowners Facing Foreclosure

Sir Francis Bacon once said that "Knowledge is power".  The Minnesota Home Ownership Center believes in taking that fact and putting it to work for families that are struggling with mortgage payments and/or are looking for information about how to avoid foreclosure.

We’re pleased to announce that FOUR new fact sheets are available thanks to our partnership with the legal assistance teams. (Special kudos and thanks to Stacey Keenan at Legal Services of Northwest Minnesota and Kari Rudd and Housing Preservation Project for their work!)

These fact sheets cover:
  • The Tax Forfeiture Process in Minnesota
  • Homeowner Association Liens
  • Manufactured Home Repossessions
  • Redeeming a home AFTER a foreclosure sale

The Center has compiled/created almost two dozen fact sheets, FAQ's and other flyers that can help when a homeowner is struggling with mortgage payments or facing foreclosure in Minnesota (all are available here).  Please feel free to print/distribute any of the fact sheets to homeowners that may benefit (Adobe Acrobat Reader required).

Do you have an idea for a fact sheet or FAQ that would benefit struggling MN homeowners? Feel free to email your ideas to Ed Nelson at the Center. Thanks!


Thursday, August 5, 2010

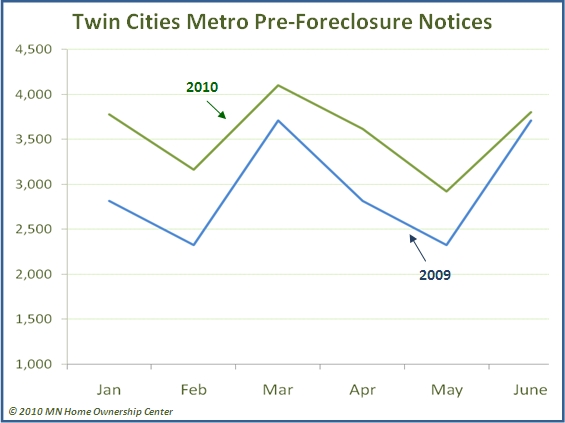
2010 Continues To Outpace 2009 (Pre-foreclosure Notices)

The Minnesota Home Ownership Center has compiled the pre-foreclosure notices received by the statewide network of Foreclosure Counselors through the end of the second quarter (June)... and 2010 continues to outpace 2009:


(Click To Enlarge)


(Click To Enlarge)

The same trend continues for the Twin Cities Metro area. 2010 pre-foreclosure numbers have outpaced 2009 numbers EVERY MONTH of the quarter:


(Click To Enlarge)

Here's how the different Metro counties break down in 2010:


(Click To Enlarge)

2009 had the SECOND HIGHEST foreclosure rate ever in the state of Minnesota. Is it possible... given the fact that the number of pre-foreclosure notices issued by lenders in 2010 is outpacing the number in 2009, that 2010 will become the second highest year on record? We welcome your opinion in the comments.

As background for new readers, Minnesota State law (MN Statute 580.021) requires that the foreclosing party provide information regarding foreclosure prevention counseling services to the mortgager (homeowner) AND provide the homeowner’s name, address, and most recent known telephone number to an approved foreclosure prevention counseling agency - BEFORE filing the notice of pendency.

Once The Minnesota Home Ownership Center's network of foreclosure counselors receives notification from the lender/servicer/homeowners association, they then contact the homeowner, and track the number of notifications received during the month in their monthly reporting to the Center.

Wednesday, July 28, 2010

Be Careful! Fraudulent Foreclosure "Help" on the Rise

The fastest-growing consumer complaint in 2009 was related to fraudulent offers to help "save" homes from foreclosure, according to a report released yesterday from the Consumer Federation of America.

The Consumer Federation of America, the National Association of Consumer Agency Administrators and the North American Consumer Protection Investigators have released  their 15th report (The 2009 Consumer Complaint Survey Report) regarding consumer complaints. The results in the report come from a survey of 33 state, county, and city agencies from 18 states on the most common consumer complaints received from January 2009 through December 2009.

According to the report, consumer complaints are on the rise, and more than half the agencies reported that they received more complaints in 2009 than in 2008. In addition, many of the complaints, like those about bogus foreclosure offerings, were related to the economy. Others included complaints about aggressive collection practices, debt settlement and other types of debt relief services, landlord and tenant problems resulting from foreclosures and job scams.

The report includes egregious examples of some of these foreclosure rescue scams and what actions many States Attorney Generals' offices are taking to combat them. 

In Minnesota... there is a coalition of over 70 organizations, agencies and companies that have come togother to fight these scams.  "Look Before You Leap" a statewide public education campaign seeking to raise public awareness about the booming foreclosure rescue scam industry and its dangerous implications for struggling and unsuspecting home owners, and to connect struggling home owners with the Center’s network of foreclosure counselors.

If you're not familiar with the campaign... you can learn more on our Facebook Page and our website.

If you, or someone you know is struggling with mortgage payments...  BE CAREFUL and don't wait until it's too late. To find your local non-profit, FREE Foreclosure Counselor, click here. For additional information about preventing foreclosure in Minnesota, click here.

Monday, July 12, 2010

Unemployed? Foreclosure Options

The Home Affordable Unemployment Program (UP) went into effect (for non-GSE mortgages) on the first of July. The UP forbearance plan allows servicers to reduce or suspend a borrower’s payment while they are receiving unemployment benefits. Servicers are required to offer an UP forbearance plan to borrowers who meet the basic HAMP eligibility guidelines and have not previously received a modification through HAMP.
Unemployed borrowers must:
  • Make the request for UP forbearance before the mortgage is seriously delinquent (before 90 days delinquent)
  • Be unemployed at the date of the request, and be able to documents that he or she will receive unemployment benefits in the month of the "Forbearance Period Effective Date"
Servicers have some leeway pursuant to investor guidelines to require a borrower to receive unemployment benefits for up to three months before the forbearance period will begin, however the homeowner can make the request as soon as they become unemployed and are able to document he or she will receive benefits.

Unemployed borrowers who do not meet the UP forbearance criteria may be offered other forbearance programs. If not offered another forbearance plan, the borrower must be evaluated for HAMP. The HAMP evaluation will not include unemployment or severance payments in the calculation of gross income.

In addition, a borrower who was denied HAMP in the past may request UP if they meet all the eligibility requirements.

The UP forbearance period lasts a minimum of three months or until the borrower has become re-employed. It is up to the servicer’s discretion as to extending the forbearance period beyond three months. During the forbearance period the borrower’s payment will be reduced to 31% or less of the gross monthly income. The servicer has the option to suspend the payments in full, again at their discretion and according to investor guidelines. Any payments due during the forbearance period must be paid in the month due or the plan may be cancelled and the borrower will not be eligible for HAMP.

For additional details on UP, you can visit the Supplemental Directives page from available on the Making Home Affordable administrative website here. 

If you're currently unemployed and receiving (or will receive) benefits... and would like to learn more about this program, contact a FREE non-profit Housing Counselor as soon as possible.  In Minnesota, you can find your local Counselor, here.


Monday, June 28, 2010

Look Before You Leap

On Tuesday, June 29th, The Minnesota Home Ownership Center will be launching “Look Before You Leap”, a statewide public education campaign seeking to raise public awareness about the booming foreclosure rescue scam industry and its dangerous implications for struggling and unsuspecting home owners, and to connect struggling home owners with the Center’s network of foreclosure counselors.

While the Center will lead the effort, we are working in partnership with NeighborWorks America and other national organizations (FDIC, Federal Trade Commission, AARP and others) and we currently have the support of over 55 Minnesota-based agencies, organizations and municipalities as well!

To readers of the Center's blog, we're asking that you help spread the word about the campaign:

a. If you're on Facebook, LIKE us ('Fan Page'):

http://www.facebook.com/LookBeforeYouLeap
  • Here you can share ideas about promoting the campaign and
  • Share the stories YOU'RE hearing about rescue scams
b. Visit the campaign website: www.LookBeforeYouLeap.org and please consider subscribing to the campaign's newsletters to keep on top of our efforts to stop foreclosure rescue scams in Minnesota.

c. Consider having your organization PARTNER with us. Partnership in the campaign is simple:

We’ll recognize your as an advocate of home owners on www.LookBeforeYouLeap.org and in our print materials, and we’ll keep you up to date with the latest campaign efforts and events.

In return, we ask that you include newsletter articles or other tools we provide in your internal communications whenever possible, and that you work with us to let your members (and their clients) know about mortgage rescue scams in Minnesota.

We’d also love to have you join us at the campaign launch event on Tuesday, June 29th @ 10:00 here at the Center (outside lot, just north of our building), followed by a brief reception in our office.

For a Google Map to our office, click here.

If you have additional questions about the campaign... or would like to learn more about becoming a partner, please contact Ed Nelson at the MN Home Ownership Center: ed[at]hocmn.org