Showing posts with label Fannie Mae. Show all posts

Thursday, February 2, 2012

Another New Refi Program? Get the Facts!


During the 2012 State of the Union Address, President Obama announced another expansion of the federal mortgage refinance program :
That's why I'm sending this Congress a plan that gives every responsible homeowner the chance to save about $3,000 a year on their mortgage, by refinancing at historically low interest rates. No more red tape. No more runaround from the banks. A small fee on the largest financial institutions will ensure that it won't add to the deficit, and will give banks that were rescued by taxpayers a chance to repay a deficit of trust. (From the State of the Union Address)


The current versions of the refinance program (HARP and HARP II) allow homeowners whose loans are owned by Fannie Mae, Freddie Mac or the Federal Housing Finance Agency, to refinance to current historically-low interest rates, EVEN IF the loan value exceeds the value of the home (allows "underwater" homeowners the opportunity to refinance).


On Wednesday, February 1st, the president released additional information about the proposed expansion of the refinance programs:


The proposed program (HARP 3?) would allow ALL homeowners who are current on their mortgage — even those who do not have loans backed by Fannie, Freddie or FHFA and even if they're  underwater on their mortgage — to also refinance their loans.


The proposal put forward by the administration includes some details about the who would qualify:

  • only owner-occupied, single-family homes are eligible.
  • Homeowners must be current on their mortgage and not had a lat payment for at least the past six months; 
  • Homeowners must have a minimum FICO credit score of 580; 
  • The loan amount cannot exceed the current federal conforming loan limit. 

For those who meet the criteria, the program would allow for a streamlined application process in which lenders would only need to confirm that a homeowner is employed and the home would not have to be appraised.


NOW... What does this REALLY mean for the average Minnesota Homeowner who might want to refinance?

  • Even though HARP II was announced in October of 2011, as of early February 2012, very few lenders and servicers have processes and procedures in place for homeowners to take advantage of the refinance program.  Any formal expansion to the program announced today would take MONTHS before a homeowner would likely be able to work out a refinance with their lender.  (See our blog post on the HARP 2.0 announcement in October, here)
  • Most Importantly, this expanded program will require CONGRESSIONAL APPROVAL. Given the fact that we are in a rather contentious election year... approval by congress is far from certain.

We'll continue to monitor this program, and if the program expansion does become a reality, we'll notify Minnesota Homeowners via this blog and our website, here.

Friday, December 2, 2011

Fannie Mae and Freddie Mac Eviction Moratoriums

On Thursday December 1st, Fannie Mae and Freddie Mac both announced eviction moratoriums that will take place over the holidays. From December 19 through January 2, families living in properties where a Fannie Mae or Freddie Mac loan has been foreclosed upon will not be evicted.


NOTE:  The legal and administrative processes for the evictions may continue during this time, but families will be able to stay in their homes.  In addition, the GSE's will continue with the foreclosure process on delinquent borrowers during this time period as well.


Large mortgage servicers often follow suit – we will updated this blog if we learn of additional banks or servicers initiating moratoriums. 


There are some nuances to the Fannie and Freddie moratoriums; additional details are available in the press releases here and here.


There is no "cold weather" rule regarding foreclosure or evictions after foreclosure in Minnesota.  If you are struggling with mortgage payments or have questions about the process, contact a FREE non-profit Homeownership Adviser that specializes in foreclosure prevention TODAY.  Waiting limits your options!

Thursday, May 19, 2011

Single Point of Contact A Reality!

Servicers must assign a "Relationship Manager" to every struggling borrower

Some exciting news was released by the administration of the Making Home Affordable program yesterday (US Treasury and Fannie Mae).  By no later than September 1st, every struggling homeowner that applies for a loan modification under Making Home Affordable must be assigned a single point of contact - who must be an employee of the servicer with a direct, toll-free telephone number - for homeowners to be able to communicate with about their documents, their application and answer questions.  This same point of contact, known as a Relationship Manager, will also be available for non-profit counselors to use when speaking with the servicer about a homeowner's situation. 

Servicers have until November 1st to assign a Relationship Manager to EXISTING MHA Consumers.  (Homeowners that are already in review or in a trial modification).

If implemented correctly... this should end a huge number of the complaints the Center hears from homeowners that are struggling with their mortgage:  "I can never speak to the same person twice,"  "They lose my paperwork,"  "I've had to send in the same document 3 or 4 times"... etc. 

According to the Supplemental Directive 11-04 for Servicers, released on May 18th:

The same relationship manager is responsible for managing the borrower relationship throughout the entire delinquency or imminent default resolution process, including any home retention and non-foreclosure liquidation options, and, if the loan is subsequently referred to foreclosure, must be available to respond to borrower inquiries regarding the status of the foreclosure.

For now, the Supplemental Directive will only be in effect for servicers that are participating in the Making Home Affordable initiative, and have a Program Participation Cap of more than $75mm.  Basically, this covers the largest 20 servicers in the country... and hopefully smaller servicers will follow suit.  Both GSEs (Fannie Mae and Freddie Mac) are currently exempt from this directive.  In Minnesota, given the partnership between Fannie Mae, the Minnesota Home Ownership Center and the Homeownership Advisors Network, there is already a single point of contact through the local non-profit counseling agency.

Will this improve the MHA program?  What other improvements do you think are necessary... leave us a comment and let us know what you think!

Wednesday, April 27, 2011

Partnership With Fannie Mae Launches In Minnesota

There's an expression in Spanish that's usually used when describing politicians:  "Los mismos perros, distintos collares"  (Same dogs, different collars).  Many homeowners struggling with mortgage payments have felt the same way about program announcements and offers of help they've heard during the housing crisis.  "It may get headlines... but can it really get me help?"

Today, the Minnesota Home Ownership and Fannie Mae announce a partnership that really is a game-changer.  This new partnership will accelerate the response time for struggling Minnesota families with loans that are owned by Fannie Mae.

Homeowners that are struggling with mortgage payments will meet with experienced foreclosure prevention counselors throughout the state that are members of the Homeownership Advisors Network to discuss their mortgage situation and determine options to avoid foreclosure. These counselors in turn will work directly with dedicated LOCAL Fannie Mae staff to find sustainable and affordable solutions for Minnesota’s homeowners.


As always... this assistance is FREE.

One of the unique aspects of this partnership has been the creation of a standardized document collection process for ALL possible loss mitigation options. Streamlining the documentation process reduces homeowner frustration and improves response times from servicers.  No longer will homeowners have to submit (and re-submit, and re-re-submit) different versions of the same documents.  This all happens ONCE - on the front end and with the assistance of a Foreclosure Counselor, and is then submitted electronically to Fannie Mae staff right here in Minnesota.  Fannie Mae staff then leverage their relationships with lenders and servicers (as the investor) to find long-term solutions.

The Center knows that one of the greatest advantages to working with a certified non-profit Housing Counseling is that homeowners  are more successful when they have access to information and the tools necessary to get a quick response to their mortgage situation.  This new partnership takes this advantage to a whole new level.

The services offered through this new partnership are only for borrowers who have a mortgage held by Fannie Mae. Homeowners can determine if Fannie Mae owns their loan by visiting www.fanniemae.com/loanlookup or by contacting Fannie Mae (Toll-Free) at 1-800-7FANNIE. Homeowners who do not have loans owned by Fannie Mae are still encouraged to contact a member of the Homeownership Advisors Network to learn more about their individual options to avoid foreclosure or to learn more about the foreclosure process by visiting www.hocmn.org or calling us at 866-462-6466.

Plus:  the Center will be launching this exciting new partnership with the assistance of Fox-9 news!  Julie Gugin from the Center, and Jeff Hayward, Sr. VP from Fannie Mae, will be on the Fox-9 Morning Show from 7-9am on the Wednesday the 27th.  Other Center staff will also be featured on both the 5:00 and 9:00pm newscasts.  (Check us out after American Idol!)  We'll update this post with links to videos as soon as they are online.

UDPATE:  Here's the piece from this morning's Fox-9 news:


(If the embedded video doesn't work... click here to view on the Fox-9 Website.

Thursday, March 3, 2011

Fannie Mae's 2010 National Housing Survey

Fannie Mae has released the findings of their latest National Housing Survey that polled homeowners and renters between October and December, 2010.

The Survey has some interesting facts and figures to digest:  
  • 65% of Americans believe that it’s a good time to buy a home. This is almost unchanged from last January, but down five points (from 70%) that thought it was a good time to buy in June (2010).
  • Just like last year… A large majority (78%) believe home prices have either bottomed or will rise over the next year. However, there have been price declines in most major markets throughout the U.S. over the past year (including here in Minnesota), meaning 78% of people polled in 2010 were wrong.
  • The percentage of those polled who believe buying a home is a safe investment has fallen six points to just 64 percent since last January’s report.

The Center believes that potential homebuyers should ALWAYS be cautious when buying their first home – and be VERY careful when hearing things like “Now is a good time to buy!” and “Housing is a safe investment!”… the “Crowd” may not aways be right.


When renters were asked why they wouldn’t purchase a home… their responses are revealing:

  • The #1 reason cited, by almost half of the respondents, was that they believe their credit was not good enough to obtain a mortgage.
  • In addition, the #2 reason, cited by 47% (multiple answers were allowed)… was that they don’t think they can afford both a mortgage and the upkeep of a home.

While the Center applauds renters that approach the idea of homeownership cautiously… there is a way to KNOW if your credit is good enough… and KNOW exactly how much you can afford to purchase – or if purchasing a home is even a good fit for you: We recommend you take a homebuyer workshop! In Minnesota, the state's premier homebuyer (pre-purchase) education curriculum is known as Home Stretch. To learn more about Home Stretch, and other services for homebuyers, visit the Center's website here.

For more information about the National Housing Survey and to see the complete report, visit Fannie Mae's website, here.  

Monday, September 27, 2010

New Fannie Mae Forbearance Program for Military Families

Fannie Mae has announced plans to give military families a break on their mortgage payments if they are struggling because of the death or injury of a service member.

Fannie says its "Unique Hardship" guidelines allow the agency to reduce or suspend borrowers' monthly payments up to six months. In addition, they will suspend reporting to credit bureaus for up to six months to minimize the impact on the borrower's credit score.

The military has established a special phone number for injured military or surviving spouses to use if they are struggling with mortgage payments: 1-877-MIL-4566.

If you or a family member are currently serving in the military... first and foremost: Thank You!  Also, there may be other helps and assistance available to you - even if your loan is not backed by Fannie Mae.  Contact a Foreclosure Counselor through the MN Home Ownership Center TODAY to learn about your options if you are struggling with mortgage payments.  To find your local non-profit, FREE Foreclosure Counselor, click here.

Friday, September 17, 2010

Fannie Mae's National Housing Survey

Fannie Mae has released the latests findings of their National Housing Survey that polled homeowners and renters between June 2010 and July 2010. These findings were compared to a similar survey released in April  (See the Center's April 22 blog post about that here). 

The Survey has some interesting facts and figures to digest:

Regarding purchasing a home:
  • 70% of Americans believe it’s a good time to buy a home - even with all of the issues we've been hearing about in the housing industry.  This number is up from 64% of respondents from the earlier survey conducted in January.
  • A large majority (78%) believe home prices have either bottomed or will rise over the next year, up from 73 percent in January.
Here's a great quote from the press release of the survey:
“Although most Americans believe that home prices have bottomed, they are adopting a much more cautious approach toward buying,” said Doug Duncan, Vice President and Chief Economist, Fannie Mae.

The Center believes that potential homebuyers should ALWAYS be cautious when buying their first home.  That's why we offer the state's premier homebuyer (pre-purchase) education curriculum, Home Stretch.  To learn more about Home Stretch, and other services for homebuyers, visit the Center's website here.

The survey has interesting information about CURRENT homeowners as well:
  • 22% of mortgage holders (homeowners) said that they have reduced their mortgage debt “significantly” over the past year, while 27 percent say they have reduced their non-mortgage debt significantly. (!!)
  • Nearly 20% of homeowners know someone who has strategically defaulted, or stopped making their mortgage payments even when they could afford to make them.
The survey also has interesting data about housing attitudes from minority groups including African Americans and Latinos. 

For more information about the survey and to see the complete report, visit Fannie Mae's website, here.  

Thursday, September 9, 2010

Subprime 2.0?

Edward Pinto, the Chief Credit Officer of Fannie Mae back in the 1980's, has written an Op-Ed for Bloomberg titled "Subprime 2.0 Is Coming Soon to a Suburb Near You" that talks about no-money down and lowered credit score requirements for government-backed loans.  [Fair warning: this op-ed is takes an EXTREMELY negative view of the loosened underwriting standards that became prevelant in the mid-2000's.]

One of the more interesting quotes in the article is where he cites the number of no-money down mortgages (or extremely low-money down) as a percentage of all loans:

In 1990, one in 200 home-purchase loans (all government insured) had a down payment of less than or equal to 3 percent. By 2003, one in seven home buyers had such a low down payment, and by 2006 about one in three put no money down.


Visually... this is what I've come up with:
 

Click to Enlarge


Now... Pinto believes we will to return to an environment of subprime lending that he refers to as “Subprime 2.0,” as the FHA continues to accept borrowers with low Fico scores and minimal down payments.

For example, the FHA’s average down payment is just 4 percent,” he wrote. “Even this meager amount disappears after adjusting for seller concessions and financed insurance premiums.

Pinto is calling for a return to hefty down payments - - a minimum of 20 percent down, with few exceptions, and believes documentation should be “iron-clad."

NOW, couple of questions for our readers (feel free to voice your opinion in the comments): 
  • What would this mean for those of us working on affordable housing issues? 
  • Would this cause more problems than it solves?
  • Are there other solutions to affordable housing... that don't involve simply lowering lending standards? 

One of the conferences that takes up the issue of affordable housing... and discusses related policy issues is the "Homes For All" Conference.  You can learn more about the conference here. 

Wednesday, May 12, 2010

Deed-For-Lease to avoid foreclosure?

Is it possible to stop being a homeowner… and become a renter of your EXISTING home? As strange as it sounds, this might just be possible with Fannie Mae’s “Deed for Lease” Program. This may allow you to be able to stay in your current property for awhile and avoid the disruption of moving your family.

The current program offers a lease of NO MORE than 12 months, at current market rental rates. If current rental rates are about the same as, or even higher than your current monthly mortgage, this program probably won’t help. The program is ONLY available for properties with mortgages backed by Fannie Mae. To see if Fannie Mae is the investor (backs) your mortgage, click here.

While the program has been around since November 2009… many people didn’t qualify becuase they had junior liens (second or third liens) on their property. Given the changes announced at the beginning of April with the new HAFA program… even homeowners with junior liens may now qualify for the ‘Deed for Lease’ program.

There are actually TWO steps that homeowners with Fannie Mae loans must ‘qualify’ for in order to be able to participate in the program.

1. First, you must sign over the deed (title) of your home in what is known as ‘Deed-in-Lieu’ of foreclosure. You have to qualify (apply) for this with your current lender… you can’t just sign over your deed and mail it back to them.

2. If your lender agrees to a Deed-in-Lieu, then you must sign-up for the “Deed-for-lease” program. There is a $75.00 per unit lease application fee as well.

The ‘Deed-For-Lease’ program is one of the few options available to avoid foreclosure for investor-owned properties… as the investor/owner can agree to a deed-in-lieu of foreclosure and their tenants can apply for the Deed-for-Lease program.

For your property to be eligible:
  • The property must be livable (qualify for a certificate of occupancy according to CURRENT local rules, codes). Repairs might be necessary to qualify or to bring the property into compliance – the program does allow for 30 days to bring it into compliance.
  • The property cannot be the focus (or participate in) any corporate, government or community neighborhood stabilization plan.
  • The property will be inspected, and an independent inspection report agrees that you have kept the property in good condition.
  • The market rental income must cover ongoing maintenance and management costs.
  • If the property is part of a homeowner's association, it must allow rental properties.

For you or your tenant to be eligible:
  • The market-rate rent on the property must be less than 31% of your gross income (unemployment income counts).
  • The number of occupants must be in compliance with local laws and homeowner association rules.
  • Occupants signing the lease must agree to a credit review and all occupants over age 18 must have a background check.
  • No sign or reports of illegal activities conducted at the property.
  • The property will be use for a personal residence.


 As long as your property is eligible, you will be assigned to a property manager who will do the inspection and manage the property once you are accepted into the program.
The property manager will meet with you within 10 days of filing your application to the “Deed for Lease” program. At the meeting you will need to fill out a formal application and pay a $75 processing fee for the application. If it's a multi-unit property, the $75 fee will be collected for each unit. The property manager will then conduct an inspection of the property to be sure it meets local codes and regulations and that the property has been adequately maintained (see above).
The advantage to this type of program is that it allows you time to start rebuilding your credit score and allows you to free up additional funds to start paying down other debt. Currently, however, the maximum lease time is 12 months… you may only be delaying the inevitable move.

Remember... you can't just sign your Deed and mail it back to the bank.  There are LOTS of steps that must be taken.  Also.. BE CAREFUL. There are LOTS of for-profit and "Foreclosure Rescue" scam companies that would love to have you sign over your deed, and will leave you without a home and without recourse.

Are you interested in learning more about the Deed-For-Lease program... or other ways to avoid or prevent foreclosure in Minnesota? Contact your local FREE (non-profit) Housing Counseling agency today to explore your options.

Thursday, April 22, 2010

Why Buy a home?

One of the first steps in a Home Stretch workshop is to explain to potential home buyers the advantages and disadvantages of homeownership.  The workshop actually starts by having people think through some of the reasons WHY they'd like to be homeowners.

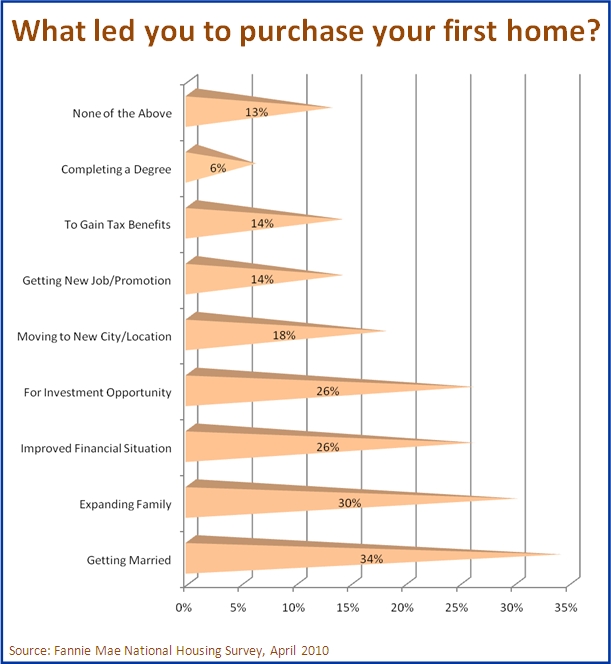
Fannie Mae's 2010 National Housing Survey asked that same question of thousands of people across the country... "What led you to purchase your first home?"  (Translation: Why'd you become a homeowner?).  The results are shown here:


(Click Image to Embiggen)

Family changes (getting married, more kids) are, apparently, the top reasons people choose to become homeowners.


PARTICIPATE IN OUR NEW SURVEY:  Knowing the possible disadvantages of homeownership (depreciation, expense, yard work, maintenance)... We'd like to know what led YOU, or, if you haven't purchased a home yet, what MIGHT LEAD you to purchase your first home.  You can answer our survey question (Just 1) here.

As a follow-up to the question we asked earlier in the week... "Why did you choose your first home (what characteristic about the home lead you to choose THAT specific property)... Our completely non-scientific online survey shows that Minnesotan's reasons for choosing their homes differ slightly from the national survey:


(Click Image to Embiggen)

Are you currently considering purchasing your first home? There are LOTS of factors to consider - there are both advantages and disadvantages to homeownership! Make sure you're fully informed about how to be a SUCCESSFUL homeowner by speaking with a Housing Counselor or by taking a Home Stretch workshop first. For more information on buying your first home in Minnesota, click here.

Monday, April 19, 2010

Survey: Reasons For Buying a Home

Fannie Mae has released its 2010 "National Housing Survey"!

The Survey, conducted in December 2009 and January 2010 (so the data is fairly recent)... surveyed consumer perspectives on a range of related issues, including: current attitudes toward the economy and housing; present conditions for homeownership; owning versus renting; the present climate for borrowing; current mortgage satisfaction; the impact of being "underwater" on borrowers; and attitudes toward defaulting. In some instances, data are compared to a 2003 study on housing by Fannie Mae.

Over the next few weeks... we'll be highlighting some of the findings of the survey.

Here's the first highlight: Reasons for Buying a Home:

Nearly two-thirds (65 percent) of survey respondents prefer owning to renting, citing non-financial reasons such as safety (43 percent) and quality of local schools (33 percent) as driving factors in wanting to own a home. 

Here's the breakdown of responses:


(Click Image to Enlarge)

One of the interesting points of that question, is that only 11% of respondents listed "Energy Efficiency" as a reason to choose a home to purchase. 11%. There seems to be a large disconnect between the push for "Green Building" and what consumers really want. (Comments are welcome in the comment section! No flame wars, please).

Care to share with us the factors that are/were important to YOU when you purchase (or purchased) YOUR first home.  Take our non-scientific survey/poll here.

Are you currently considering purchasing your first home?  There are LOTS of factors to consider... as you can see from the Survey Results above.  Make sure you're fully informed about how to be a SUCCESSFUL homeowner by speaking with a Housing Counselor or by taking a Home Stretch workshop first.  For more information on buying your first home in Minnesota, click here.

Friday, February 27, 2009

Food For Thought - Private Investor Foreclosures

Here’s some food for thought… President Obama’s Homeowner Affordability and Stability Plan, the details of which will be available next week, focuses heavily on Fannie Mae and Freddie Mac backed mortgages.

However, according to a presentation given by James Lockhart , the Director of the Federal Housing Finance Agency (FHFA), to the Association of Government Accountants on the 19th of February, third quarter 2008 national default information shows that while private label (private investor) backed mortgages are only 16% of all outstanding mortgages, they account for 62% of all seriously delinquent mortgages.

The FHFA report defines seriously delinquent as a payment that is at least 90-days past due.

In addition, Freddie and Fannie account for 56% of all outstanding mortgages, but only 19% of seriously delinquent mortgages.

PLUS, mortgages held in a bank’s portfolio account for 16% of all outstanding mortgages, and only 6% of seriously delinquent mortgages.


Can we infer anything from this information? Prior to 2008, and now again in 2009, Fannie and Freddie required that their home buyers complete a certified Home Buyer Education Workshop - - known as Home Stretch in Minnesota.

Many of the bank portfolio loans – especially first-time buyer programs and low- to moderate-buyer programs, ALSO required home buyer education - - especially in Minnesota. Is this a fair inference? Feel free to discuss in the comments.

The Minnesota Home Ownership Center believes that Home Stretch, homebuyer education and counseling is key to making informed decisions about the important choices related to homeownership. Is homeownership right for YOU? Home Stretch can help answer that question.

Are you having difficulty making a payment? Whether your mortgage is owned by Fannie Mae or Freddie Mac - - or any other lender or servicer, the Minnesota Home Ownership Center’s network of Foreclosure Counselors can help. Click here for more information.