Monday, October 24, 2011

HARP Changes - What We Know, What We Don't

It is likely that President Obama will be announcing some major changes to the Home Affordable Refinance Program (HARP) on Monday, October 24th, 2011.  The Federal Housing Finance Agency, the agency that regulates Fannie Mae and Freddie Mac as well as the 12 Federal Home Loan Banks throughout the country, has issued a press release outlining some of the important changes to the HARP program.


What We Know:

  • The goal is to prevent additional foreclosures by allowing additional underwater homeowners to refinance their mortgages at today's low interest rates and/or shortening the term of their mortgage.
  • Most importantly, the current 125% Loan to Value limit (LTV Ceiling) will be removed, but there is still a MINIMUM LTV of 80%.  Borrowers that are underwater by any amount greater than 80% may be able to participate in HARP.
  • Borrowers fees to participate in HARP will be reduced.
  • To participate, borrowers must be current, have not been late on a payment in the last 12 months, and have a verifiable source of income.  Actual affordability ratio (how much income needed) has not been released.
  • The new guidelines should waive the need for a full appraisal if a reliable Automated Valuation Model (AVM) is available on the property.
  • Participation in HARP is a one-time opportunity.  If a homeowner has refinanced under the original HARP guidelines, they will NOT be able to refinance a second time under these new changes.
  • Only mortgages that are owned by the Government Sponsored Enterprises (GSE's), -- Fannie Mae and Freddie Mac -- will be participating in the new program.  The mortgage must have been sold to Fannie Mae or Freddie Mac on or before May 31, 2009.  To determine if your loan is owned by Fannie or Freddie, you can use the following links:


What We Don't Know
This blog post was written on Monday 10/24/2011... and many of the details may change over time.  Please call a non-profit housing counselor for additional details about these HARP changes... or any other question you may have about your mortgage.


  • When will homeowners actually be able to refinance their Freddie Mac- or Fannie Mae-backed mortgage?  Guidelines on the new program will be sent to lenders and servicers by November 15th.  After that, the lenders/servicers will have to convert those guidelines into actual policies and procedures.  This means that it may be mid-December or even early 2012 before a homeowner can actually participate.  In addition, the concept of the program is complicated by the fact that certain servicers DO NOT ORIGINATE loans and may not have the capacity to originate the new HARP loan - without extensive (and time-consuming) changes to their internal systems.  PLUS, as we've seen with the original HARP program, there may be inconsistencies from one servicer to another.
  • What will happen to homeowners in the following circumstances:
    • Multiple mortgages - second lien holders will have to agree to 're-subordinate' their loan to the newly refinanced loan.  While there is no risk to the junior lien holders... we don't know which, if any, second lien holders will agree re-subordinate their mortgages.
    • Private Mortgage Insurance Holders - PMI holders have agreed to make the transfer of insurance from one loan to another easier... the details are still being worked out. 
Once again... as the guidelines to servicers and lenders will not be available until November 15th... it will take several additional weeks for the lenders and servicers to convert those guidelines into policies and procedures, meaning that it may a couple of months before homeowners can access this new phase of HARP.


    Monday, October 3, 2011

    Reminder on Deficiency Judgments


    The Wall Street Journal published an excellent article this weekend on the dangers of deficiency judgments.


    A deficiency judgment is “a judgment lien against a debtor, defendant or borrower whose foreclosure sale did not produce sufficient funds to pay the mortgage in full.”


    In plain English: a homeowner can be sued for the difference between the amount the bank received when they auctioned off the house at the Sheriff’s sale, and the amount of the outstanding mortgages.


    In the Wall Street Journal article, many of the former homeowners had purchased in Florida, where judgment can be sought on ANY mortgage deficiency.  However, Minnesota is a ‘Non-Recourse’ state. This means that FIRST lien holders CANNOT seek judgment (cannot sue) former homeowners for outstanding funds*.


    HOWEVER... any “Junior”, or "Second" lien-holders CAN. If there is more than one mortgage on the property – or if there is a line of credit or HELOC taken out against the property – THOSE lenders CAN sue the former property owner for payment of any outstanding debt.


    Lenders can take up to SIX YEARS in Minnesota to decide whether or not to sue for any deficiency.  In many cases, the lender won't be the ones seeking judgment.  They'll simply sell the outstanding deficiency to collections companies, for pennies on the dollar, who will then be relentless in their efforts to collect.


    One of the scariest quotes from the article comes from a representative of one of the collection agencies:
    "We are waiting for the economy to somewhat heal so that it's a better time to go after people," says Douglas Hannah, managing director of Silverleaf.


    The MN Home Ownership Center has a helpful fact sheet on its website about deficiency judgments. You can download the fact sheet here.


    Deficiency Judgments are just ONE of the MANY considerations struggling homeowners need to think about when facing a possible foreclosure. If you, or someone you know is struggling with mortgage payments... don't wait until it's too late. To find your local non-profit, FREE Foreclosure Counselor, click here. For additional information about preventing foreclosure in Minnesota, click here.


    * There are situations in which a homeowner can open themselves up to deficiency on a first lien.  In a short sale situation, if the negotiations aren't carried out properly homeowners may unwittingly sign paperwork that allows the bank to seek judgement.  This occurs when the bank is willing to release the lien so a short sale can occur, but does not release the underlying debt.  Homeowners that are selling in a short sale situation need to be EXTREMELY careful about the documents they sign before selling.

    Thursday, September 29, 2011

    Two Minnesota Housing Agencies Receive Expansion Grants

    NeighborWorks America invests in expanding services in Minnesota.


    On Friday, September 23, NeighborWorks America announced $3.65 million in grant funding specifically designed for nonprofits to increase their services for underserved communities by expanding the geographic reach of programs that have already been successfully established. 

    NeighborWorks America hopes this grant funding will help agencies with a track record of successful programs bring their initiatives to even more communities in need. Among the 25 organizations receiving grant funds are two Minnesota-based agencies: Southwest Minnesota Housing Partnership and Dayton’s Bluff Neighborhood Housing Services.

    The Southwest Minnesota Housing Partnership works to provide a sufficient supply of adequate, safe, sanitary and affordable dwellings for the people of southwestern Minnesota and is a member of the Center’s Homeownership Advisor’s Network. 

    Dayton’s Bluff Neighborhood Housing Services provides owner-occupied rehab lending and construction management, homeownership education counseling, financial entry assistance, purchase-rehab-resale and new construction. Both of these organizations are making valuable contributions towards enabling successful homeownership for residents of Minnesota. 

    Congratulations to both organizations on receiving a NeighborWorks America grant to continue and expand your good work!

    For more information and a list of all 25 grant recipients, visit the NeighborWorks America news site.


    Wednesday, September 28, 2011

    Foreclosure Counseling - NFMC Report

    Last week, NeighborWorks America released its 6th report to Congress on the National Foreclosure Mitigation Counseling program (NFMC).  The full report is available here.


    Once again, the most recent report shows that while foreclosures continue to impact the nation's housing market, foreclosure intervention/prevention counseling WORKS.


    Here are just a few of the highlights from the report:

    • Homeowners who receive foreclosure prevention counseling are 70% more likely to cure their foreclosure than similar homeowners that don't receive counseling.
    • Counseling clients that received loan modifications were able to reduce their monthly loan payments an additional $260 MORE than homeowners that don't work with a counselor.  The cumulative savings for struggling homeowners?  More than $560 Billion (with a "B") dollars PER YEAR.

    One of the interesting shifts highlighted in the report is the fact that, for the first time, a majority of the clients nationwide that sought foreclosure counseling (53%) hold fixed-rate mortgages with interest rates below 8%.  In October of 2008... only 30% of homeowners were in the same situation.  The foreclosure crisis in the U.S. is definitively no longer just a sub-prime issue.  Over 60% of homeowners cite unemployment or underemployment as the primary reason they are struggling with their mortgage payment.

    All of this information is very similar to the information we've seen in Minnesota.  The Center's 2010 report on the foreclosure prevention counseling is available here.

    Given that foreclosures in Minnesota have once again begun to tick upwards... it is vitally important that homeowners seek the help of a certified non-profit Housing Counseling agency when they're struggling with their mortgage.  Do you know someone that's struggling to make their mortgage payment?  Let them know about free counseling in Minnesota by having them visit: www.hocmn.org for more information.

    Wednesday, September 14, 2011

    Finally - Major Changes in the Mortgage Industry

    Major regulatory changes are shaking up the how servicers deal with delinquent homeowners.


    The number one complaint the Center hears from struggling homeowners is how difficult it is to work with their bank or servicer.  Common complaints include getting lost in overly-complicated voice-mail systems, being routed from one department to another, never being able to speak with the same agent or representative twice, and constantly being told conflicting information when speaking with different agents.  However... a major change is on the horizon that should put an end to all this confusion:


    The Making Home Affordable (MHA) program has updated their servicer guidance to require a “Single Point of Contact for Borrower Assistance”. In essence, the new guidance requires servicers to provide a single relationship manager to each struggling homeowner that is applying for help through the Making Home Affordable program or any other foreclosure-prevention option.  This includes HAMP, HAFA, UP and any in-house modification MHA servicers may provide.


    The relationship manager will be responsible for communicating with the borrower, tracking their documents, responding to inquiries and coordinating the communication with any other bank/servicer employees. Homeowners should receive notice about being assigned to a contact as well as a toll-free number to use and information about the preferred method by which they should send documents to the servicer. The guidelines state that the relationship manager must be a full-time employee of the servicer, not a sub-contractor, who should be fully trained on the MHA program and the other in-house loss mitigation options available to clients.  Even if the client is not eligible for any loss mitigation options, and the loan is foreclosed, the relationship manager must still be available to the homeowner to answer questions about the status of the foreclosure.


    It remains to be seen how well the servicers do implementing these changes, but this is good news for struggling homeowners AND their housing counselors.


    Are you, or someone you know struggling with mortgage payments?  FREE, non-biased housing counselors are available to help!  Don't delay, visit www.hocmn.org to learn more about ways to avoid foreclosure in Minnesota.

    Wednesday, August 31, 2011

    HUD Extends Application Period for EHLP

    On Tuesday, the US Department of Housing and Urban Development (HUD) and NeighborWorks America announced that they have reopened the application process for the Emergency Homeowners’ Loan Program (EHLP).


    EHLP offers an ‘emergency bridge loan’ (mortgage payment assistance) of up to $50,000 for qualified homeowners who have experienced an involuntary reduction in income (due to medical or employment issues) and are at risk of foreclosure.


    Several thousand EHLP pre-applications were received during the original enrollment period in July.  The majority of those did not meet the strict guidelines established by HUD and the Dodd-Frank Act.   Because of the high disqualification rate, HUD anticipates that there will be funding available to reach additional struggling homeowners, and has decided give additional homeowners the opportunity to apply for these funds during an “Open Enrollment” period.


    However, homeowners need to understand two key points about this new open enrollment period:

    1. The strict qualifying guidelines still apply
    2. Open enrollment requires a COMPLETE application and supporting documentation

    The strict guidelines include (but certainly aren’t limited to):

    • 90 days late as of June 1, 2011 and homeowners must still be at least 90 days late 
    • Must have experienced a documentable reduction of 15% in their income due to the economy or a medical condition (involuntary layoff or wage reduction, for example)
    • No sheriff’s sale scheduled within the next 30 days 

    EHLP funds are provided to qualified homeowners on a first-come, first-served basis and it is critical homeowners provide all required application documents as quickly as possible, or they may risk losing the opportunity to apply for assistance.  In Minnesota homeowners should submit all documents before 4:00pm on Thursday, September 15th and understand that as the September 15th deadline nears, there may not be enough time to review application documents.  Submission of documentation does NOT guarantee that an application will be reviewed or accepted by HUD.


    What should interested homeowners do?
    Homeowners that are interested in applying for EHLP during the open enrollment period should contact their local Housing Counseling agency that is participating in open enrollment to see if they meet the strict program requirements and for information on how to apply.

    • Hennepin County residents, call Community Action Partnership of Suburban Hennepin at (952) 933-1993.
    • Carver, Scott & Washington County residents, call Carver County CDA at (952) 658-7878.
    • Dakota County Residents, Call Dakota County CDA at (651) 675-4555.
    • Residents of ALL OTHER MINNESOTA Counties, call LSS Financial Counseling at (800) 777-7419.

    Additional information about EHLP and the strict eligibility requirements are also available on the EHLP Minnesota website:  www.EHLPMinnesota.com.  

    Wednesday, August 3, 2011

    Homeownership Issues & The 2011 Legislative Session

    This post is a guest post by Laura Hodges, AmeriCorps Member with the MN Home Ownership Center:
     
    Click To Enlarge
    (c) inspidlife (Used Under Creative Commons License)
    http://www.flickr.com/photos/soaptrail/
    2011 Legislative Update 

    The 2011 legislative session at times got hotter than a July weekend. Combining that with the government shut down, Minnesota citizens might have questioned if the politicians were getting anything done. 
    Well I am happy to report that lawmakers implemented two agreements during the most recent legislative session that offer additional protections to homeowners beginning August 1, 2011:

    Mortgage Ownership Disclosure (Link)
    This law updates an existing law that requires mortgage servicers to disclose to a borrower, upon request, who actually owns their mortgage loan and the contact information.  While this may be helpful for homeowners, it is especially helpful for Homeownership Advisors (foreclosure counselors) when working with homeowners facing foreclosure as the knowledge of who really owns the loan can be helpful when negotiating workout options.  

    Extended Redemption Period for Reverse Mortgage Holders
    The other change that was passed during the legislative session involves Reverse Mortgages. The law grants reverse mortgage borrowers, who have had a sheriff sale due to foreclosure, an extended redemption period of 12 months. This extension will give time for the homeowner to regain ownership if they can pay off the mortgage loan in full, or can be used as extended time to find alternative housing options. This change is welcome news for many reverse mortgage holders.


    The Minnesota Homeownership Center would like to thank Laura for her valuable contributions to our work and mission over the past year.  You've been a great member of our team, and we wish you the best as you move on to pursue other goals!

    Tuesday, July 19, 2011

    Court Ruling in Rochester May Affect Foreclosures in Minnesota

    When you think of Rochester Minnesota - you may think of the winding Zumbro river, the large IBM site or, of course, the Mayo Clinic.  It's not often you think of Rochester as a setting for courtroom drama that may change the way banks and their attorneys handle foreclosures.  However, a recent court decision in Olmsted County may do just that.


    A foreclosure that had taken place in August of 2010 was ruled invalid by Olmsted County District Judge Jodi Williamson, because the Notice of Foreclosure Sale (Sheriff's Sale) was posted in a small newspaper in a neighboring township - not in a publication distributed in the area where the house was located.


    The State of Minnesota requires that lenders notify homeowners of a pending sale by attempting to serve the occupant of the property with the Sale Notice (via local Sheriff or process server) AND publish, for 6 consecutive weeks, the date and location of the sale in a local publication.  


    According to housing counselors in the Rochester area, many attorneys use the smaller nearby papers due to the costs of publishing foreclosure notices in the Rochester paper.  According to sources, the cost to publish a foreclosure notice in the Rochester Post Bulletin was the highest in the state.  


    If this ruling holds, it will mean that some foreclosures that took place in Rochester will be ruled invalid.  


    However, this won't be the end of foreclosures in Rochester as:

    1. Many homeowners would have been notified via process server anyway, and
    2. Most lenders will simply refile the foreclosure, obtain a new sale date from the Sheriffs Department and notify homeowners again, this time complying with the state statute.  

    It's still great to see that Minnesota is "ahead of the curve" when it comes to consumer protections under the law.  Even when a bank must proceed with a foreclosure - if there are no other options - they must comply with the law.


    If you're a homeowner struggling with your mortgage - don't wait for a legal ruling or hope for a legal loophole to avoid facing your foreclosure issue - non-profit (free) housing counseling is available throughout the state - including Olmsted County - to help YOU avoid foreclosure.  Don't delay, visit the Minnesota Home Ownership Center's website HERE to find your local counselor.

    Thursday, July 7, 2011

    New Video - Emergency Homeowners' Loan Program

    The Minnesota Homeownership Center has created a new video to assist consumers in understanding the new Emergency Homeowners' Loan Program.


    As yesterday's post mentioned, under EHLP 1,405 selected (unemployed/underemployed) Minnesota homeowners will receive up to $50,000 in interest-free loans over the next two years to help pay mortgage costs. The loans are also 100% forgivable for homeowners who stay in their home for 5 years following the program’s completion.


    The program can be a little difficult to understand, as it has very strict qualification guidelines and actually rolls out in several phases over the next few months.  MN Housing and the MN Homeownership Center have created a website: www.EHLPMinnesota.com to try and outline some of the program guidelines and explain to consumers how the program works.


    NOW, the Center has added a new video that explains, in seven short minutes, the basics of the EHLP program and how to apply.  


    Please feel free to share this video or embed it on your website!  If you do share it, please let us know in the comments or by email: ed@hocmn.org.


    Here's the video:


    To link to the video from your site, blog or email, use: http://youtu.be/qtQ2NBlxYFE


    To embed the video on your site, visit the link above and click on the "Share" button below the video.

    Wednesday, July 6, 2011

    New Foreclosure Prevention Assistance Program - EHLP

    Homeowners facing foreclosure due to involuntary unemployment, underemployment or medical issues are eligible to benefit from a new federal program: the Emergency Homeowners' Loan Program (EHLP).

    The program is only accepting applications between July 5 & July 22. Under this program, more than 1,400 selected Minnesota homeowners will receive up to $50,000 in interest-free loans over the next two years to help pay mortgage costs. The loans are also 100% forgivable for homeowners who stay in their home for 5 years following the program's completion.

    Homeowners eligible to apply for the federal program must meet several criteria, including:

    • Have faced an income decline of at least 15% due to involuntary unemployment, underemployment or medical issues
    • Have been unable to make their mortgage payment for at least 3 months prior to June 1, 2011
    • Reside in the mortgaged property


    Unemployed or underemployed homeowners should visit the program's Minnesota website at www.EHLPMinnesota.com  to learn more about the program, verify eligibility and download a pre-application.

    Remember: The deadline to apply for this one-of-a-kind program is 4:30p.m. on Friday, July 22.

    Homeowners are also being warned to steer clear of scams.  There is no charge to apply for EHLP and checking eligibility and filling out the pre-application is simple.  An offer to help fill out EHLP forms for a fee or anyone who guarantees that a pre-application will result in acceptance in the program in exchange for money is a scam. 


    Visit www.EHLPMinnesota.com for more information.


    ------------------------------------------------------------------------------------------------------


    CALL TO ACTION:  Help Us Spread The Word!

    If you know of unemployed/underemployed homeowners who are struggling with mortgage payments, we ask that you spread the word to them about this unique, and short-lived, opportunity.

    Below you will find additional tools that you can use to help spread the word (Links to documents):


    Maybe a link on your website?  An email to friends/family or clients?  A handout at the cash register or inserted into clients purchases? A blog post on your company or personal blog?  WHATEVER!  We'd love to hear about it!  Post a comment about how you're helping, or visit our Facebook page and share your outreach ideas.  THANKS! 

    Tuesday, May 24, 2011

    Dodd-Frank Reform Act & QRM Impact on Minnesota

    Training for Housing, Lending & Real Estate professionals.

    On Tuesday, May 24th, the Minneapolis/St. Paul Business Journal reported that, according the Federal Reserve Bank of Minneapolis, one in three banks in Minnesota are still struggling to recover from the foreclosure/financial crisis.

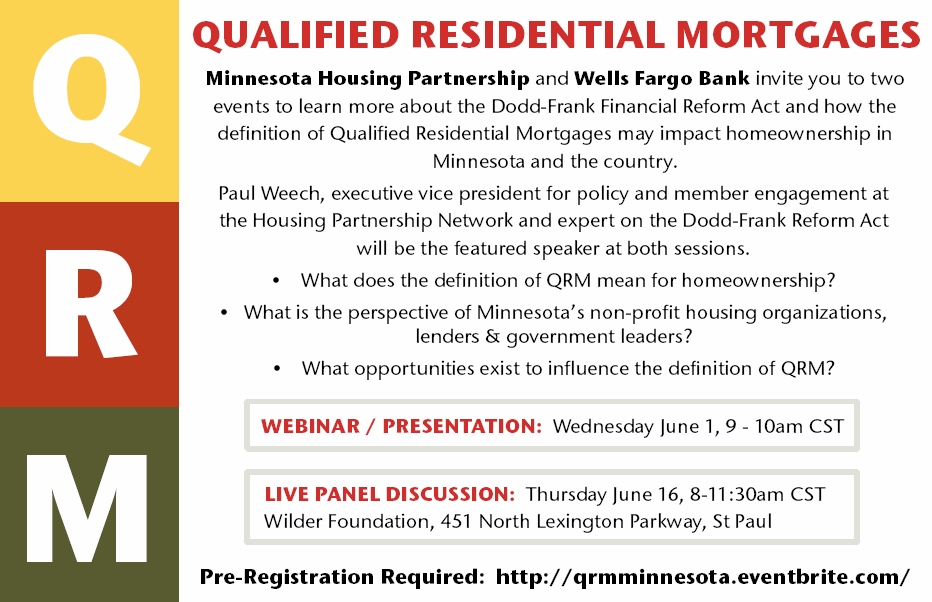
    With this backdrop... Minnesota's mortgage lenders now face the uncertainties created by the implementation of the definition of "Qualified Residential Mortgage" (Section 941) of the Dodd-Frank Reform Act.  This section of the Act will require all financial institutions that securitize mortgage loans to retain at least five percent of the credit risk, and proposes strict definitions for Qualified Residential Mortgages that can be securitized.

    Two of the Minnesota Homeownership Center's partners, Minnesota Housing Partnership and Wells Fargo will be hosting two events offering affordable housing advocates, lending and Real Estate professionals the opportunity to learn more about the Dodd-Frank Financial Reform Act and how the definition of Qualified Residential Mortgages may impact affordable homeownership in Minnesota and the country.

    Paul Weech, executive vice president for policy and member engagement at the Housing Partnership Network and expert on the Dodd-Frank Reform Act will be the featured speaker at both sessions.

    Participants will learn about:
    • What does the definition of QRM mean for homeownership?
    • What is the perspective of Minnesota’s non-profit housing organizations, lenders & government leaders of QRM?
    • What opportunities exist to influence the final definition of QRM?

    SESSION 1: Webinar
    Date & Time: Wednesday, June 1st, 9-10am CST

    SESSION 2: Live Panel Discussion
    Date & Time: Thursday, June 16th, 8 - 11:30am CST
    Location: Wilder Foundation, St. Paul, MN

    To register (pre-registration required) or to learn more about the topics covered, visit the registration page here: http://qrmminnesota.eventbrite.com/

    Friday, May 20, 2011

    New Mortgage Disclosure Forms

    Share your opinion with the Consumer Financial Protection Bureau


    It’s not very often that the general public gets to weigh in on items that will affect the entire mortgage industry. Recently, the Consumer Financial Protection Bureau (CFPB) released drafts of a new one-page (two-sided) mortgage disclosure form and is asking for YOUR opinion. The final form will combine the two mortgage disclosures that are currently required -- the federal Truth in Lending Act (TILA) mortgage disclosure and the Real Estate Settlement Procedures Act (RESPA) Good Faith Estimate -- into one two-page form, down from the current five pages.

    While these forms are covered in-depth in the Home Stretch workshop, they certainly can be confusing for the average homebuyer, and the CFPB is asking the general public to offer their opinion on which of the two is easier for you (or your customers) to understand.

    Both versions show the key loan terms like the interest rate, the monthly loan payment, any closing costs and taxes. Borrowers can quickly see how much they'll be paying per month, and, if the loan is adjustable, how those payments might change throughout the life of the loan.

    Interestingly, the form also shows the Annual Percentage Rate (APR) paid over a five-year period, along with the amount of principal you will have paid off in five years (real equity).

    The CFPB will be working on these forms until July of 2012, but over the next few months, the agency will be revising and re-uploading the form(s) on its site based on the input it receives.

    So… go vote! Let your opinion be heard. Then come back and let us know which one you prefer in the comments. The two forms are available here.

    When comparing the forms, we recommend that you focus on what information mortgage lenders and/or brokers should share with homebuyers to make the process as easily understood and transparent as possible. Remember… our goal at the Minnesota Home Ownership Center, and of our lender and real estate partners, is successful homeownership. Which form do you think will best help potential buyers in that respect?

    Are you a Minnesota resident thinking of buying your first home? Do terms like TILA, RESPA and GFE sound like a foreign language? You can learn more about these, and many more, terms, the mortgage loan process and the best steps to follow to be a successful homeowner by taking a Home Stretch workshop. For more information, click here.

    Thursday, May 19, 2011

    Single Point of Contact A Reality!

    Servicers must assign a "Relationship Manager" to every struggling borrower

    Some exciting news was released by the administration of the Making Home Affordable program yesterday (US Treasury and Fannie Mae).  By no later than September 1st, every struggling homeowner that applies for a loan modification under Making Home Affordable must be assigned a single point of contact - who must be an employee of the servicer with a direct, toll-free telephone number - for homeowners to be able to communicate with about their documents, their application and answer questions.  This same point of contact, known as a Relationship Manager, will also be available for non-profit counselors to use when speaking with the servicer about a homeowner's situation. 

    Servicers have until November 1st to assign a Relationship Manager to EXISTING MHA Consumers.  (Homeowners that are already in review or in a trial modification).

    If implemented correctly... this should end a huge number of the complaints the Center hears from homeowners that are struggling with their mortgage:  "I can never speak to the same person twice,"  "They lose my paperwork,"  "I've had to send in the same document 3 or 4 times"... etc. 

    According to the Supplemental Directive 11-04 for Servicers, released on May 18th:

    The same relationship manager is responsible for managing the borrower relationship throughout the entire delinquency or imminent default resolution process, including any home retention and non-foreclosure liquidation options, and, if the loan is subsequently referred to foreclosure, must be available to respond to borrower inquiries regarding the status of the foreclosure.

    For now, the Supplemental Directive will only be in effect for servicers that are participating in the Making Home Affordable initiative, and have a Program Participation Cap of more than $75mm.  Basically, this covers the largest 20 servicers in the country... and hopefully smaller servicers will follow suit.  Both GSEs (Fannie Mae and Freddie Mac) are currently exempt from this directive.  In Minnesota, given the partnership between Fannie Mae, the Minnesota Home Ownership Center and the Homeownership Advisors Network, there is already a single point of contact through the local non-profit counseling agency.

    Will this improve the MHA program?  What other improvements do you think are necessary... leave us a comment and let us know what you think!

    Monday, May 16, 2011

    Preforeclosure Notices Drop 21% in First Quarter

    The beginning of the end of the foreclosure crisis in Minnesota?


    Source: revjavadude
    The Minnesota Homeownership Center has released its most recent report on the aggregate number of Preforeclosure Notices received by foreclosure counselors in the Homeownership Advisors Network and the numbers signal a possible light at the end of the tunnel for the foreclosure crisis that has affected the housing industry and Minnesota families for more than four years.

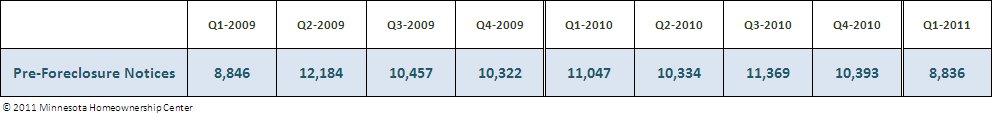
    In the first quarter of 2011, members of the Homeownership Advisors Network received 14,595 preforeclosure notices, a drop of 21% from the same time period a year ago, and a 15% drop in the number of notices received last quarter (Q4, 2010).

    This number reflects the lowest number received by counseling agencies since we started compiling the data in the first quarter of 2009:


    Click To Enlarge


    The drop in notices received by counseling organizations in the Twin Cities metro was equally dramatic. 8,836 notices were received, a 20% decrease over the same time period in 2010, and, like what we saw statewide, a 15% drop in the number of notices received last quarter:


    It’s certainly too early to celebrate, as the number still means that almost 15,000 Minnesota families are still dangerously close to losing their homes to foreclosure and thousands of others are still struggling with their monthly mortgage payment. In addition, the most recent (Q1) Sheriff Sale numbers from HousingLink while down, still reflect numbers that are 400% higher than pre-crisis numbers. But it might be time to be cautiously optimistic that the very worst of the crisis is over. Remember, the housing crisis was a overwhelming painful for Minnesota and families involved and recovery will take MANY years.


    If you or someone you know is struggling with their mortgage payment, new programs, resources and assistance are becoming available all the time. DON’T GIVE UP… contact a foreclosure counselor that is a member of the Homeownership Advisors Network TODAY to see if there’s help available for YOU to avoid foreclosure. Even if you’re not yet behind, now is the time to call. To find your local foreclosure counselor, click here.

    For additional information about the statutory requirement for pre-foreclosure notices, visit the Office of Revisor of Statutes website here.

    Thursday, May 12, 2011

    Foreclosure Moratorium in Minnesota?

    Disaster Areas in Minnesota Affected


    On Tuesday May 11th, the Federal Government announced that federal disaster aid had been made available to Minnesota to assist with the state and local recovery areas from the spring storms and flooding that started back in mid-March and continues through today. While this means that Federal funding is available to state and local governments to help with protection and recovery efforts, there is also a housing-related issue that this National Disaster declaration puts into place: a 90 day moratorium on any foreclosure action on any FHA backed loans for consumers affected by the storms/flooding. (Fannie Mae and Freddie Mac and a handful of private lenders/servicers also have standing policies about halting foreclosures in Disaster Areas.)

    The counties affected by the National Disaster declaration are: Big Stone, Blue Earth, Brown, Carver, Chippewa, Clay, Grant, Lac qui Parle, Le Sueur, Lyon, McLeod, Nicollet, Redwood, Renville, Scott, Sibley, Stevens, Traverse, Wilkin, and Yellow Medicine counties.

    Remember, the moratorium and other tools that HUD has put in place for lenders (mortgagees) to use are only available to homeowners that have been DIRECTLY affected by the disaster.

    In a clarification conversation the MN Home Ownership Center had with local HUD representatives in Minnesota, the word AFFECTED can mean:

    • Either the property itself was damaged or destroyed by the storms/flooding,
    or

    • The homeowner’s income was affected by the flooding (their place of work or business is flooded, for example)

    Affected homeowners who have an FHA-backed mortgage are instructed to call their lender to see what tools FHA has in place for helping with foreclosure avoidance following the disaster declaration.

    In addition, the Homeownership Advisors Network is ready to assist ANY homeowner that is struggling with mortgage payments, especially those homeowners that have been affected by the spring storms.

    Don’t delay, contact a foreclosure counselor that is a member of the Homeownership Advisors Network TODAY to see if there’s help available for YOU to avoid foreclosure. Even if you’re not yet behind, now is the time to call. To find your local foreclosure counselor, click here.

    Wednesday, May 4, 2011

    Dangerously Unprepared

    Buying a home without Home Stretch


    Even after all of the news about the dangers associated with purchasing a home without being fully prepared, it appears as though the message still isn’t getting out to potential homebuyers. According to a newly-released survey from Zillow Mortgage Marketplace, a surprisingly high number of people don't understand the home buying process, especially the information about obtaining a mortgage, and may be making poor financial decisions as a result.

    Those surveyed answered basic questions about mortgage information and terminology wrong almost half of the time. Forty-four percent of buyers admitted that they are not confident in their knowledge of mortgages or the mortgage process!


    Other findings include:


    • About 77% of prospective homebuyers did not clearly understand what factors are involved in determining a mortgage interest rate, believing that annual income is an important determinant.
    • More than one-third (34%) of the respondents did not understand that lender fees are negotiable and that they vary by lender. They believe lenders are required by law to charge the same fees for credit reports and appraisals.
    • More than one-third (37%) of prospective home buyers who were polled believe that pre-qualifying for a loan means they have secured financing. The reality is that "pre-qualification" is used to describe an earlier step in the process when a lender or Homeownership Advisor approximates how much you can afford, but does not pull your full credit report or request any sort of documentation to verify the information you provide. A pre-qualification is NOT a pre-approval.

    Before you start the process of making what may be the LARGEST PURCHASE IN YOUR LIFE, we highly recommend that you participate in a Home Stretch workshop. This is a class for potential homebuyers that is recognized nationally as a proven tool for preparing Minnesotans to be successful homeowners. There is an entire section of the Home Stretch workshop dedicated to fully understanding mortgage loan terminology, how to shop for a loan, how credit affects loan payments and how to avoid being taken advantage of when choosing a loan.

    Year after year, Home Stretch participants report that help with understanding mortgages and the loan process was the MOST HELPFUL part of the workshop. In fact, NINETY-FIVE PERCENT of Home Stretch participants report that their participation in Home Stretch will help in the process of buying a home, and 98% would recommend the workshop to someone else. (For more information about consumer satisfaction with Home Stretch, view the most recent report here).


    Are you thinking of purchasing a home in Minnesota? You can learn more about the mortgage loan process - - and the entire home buying process by taking a Home Stretch workshop. For more information, click here.

    Monday, May 2, 2011

    HECAT Request For Proposals Available

    As many of our readers know, the State of Minnesota is unique in that we are the only state in the country with a dedicated pool of funds that provides financial support to eligible non-profit organizations to deliver a variety of homebuyer/homeowner education, counseling and training services to Minnesotans. This dedicated pool is known as HECAT (The Homeownership Education, Counseling and Training Fund).

    Some of the valuable services that are funded through HECAT include:
    • Pre-purchase education and counseling (Home Stretch),
    • Post-purchase education and counseling,
    • Home equity conversion counseling (Reverse Mortgages) and
    • Foreclosure prevention counseling
    Funds for HECAT come from a public-private partnership of four agencies and organizations that are fully invested in ensuring that Minnesotans have access to the education and counseling tools necessary to achieve successful (sustainable) home ownership:


    Each of the four funding partners not only contribute financial resources they also actively participate in the grant-making process and provide technical assistance throughout the year.

    The Request for Proposal (RFP) for funding for programs in 2011 and 2012 (funding year runs from October 1st through September 30th) is NOW OPEN.  The deadline for applications is 5:00pm on Wednesday, June 1st.  This is a STRICT deadline.

    For more information about HECAT, or to view the RFP and even lists of award recipients from previous years, visit the Minnesota Housing website... here.

    Wednesday, April 27, 2011

    Partnership With Fannie Mae Launches In Minnesota

    There's an expression in Spanish that's usually used when describing politicians:  "Los mismos perros, distintos collares"  (Same dogs, different collars).  Many homeowners struggling with mortgage payments have felt the same way about program announcements and offers of help they've heard during the housing crisis.  "It may get headlines... but can it really get me help?"

    Today, the Minnesota Home Ownership and Fannie Mae announce a partnership that really is a game-changer.  This new partnership will accelerate the response time for struggling Minnesota families with loans that are owned by Fannie Mae.

    Homeowners that are struggling with mortgage payments will meet with experienced foreclosure prevention counselors throughout the state that are members of the Homeownership Advisors Network to discuss their mortgage situation and determine options to avoid foreclosure. These counselors in turn will work directly with dedicated LOCAL Fannie Mae staff to find sustainable and affordable solutions for Minnesota’s homeowners.


    As always... this assistance is FREE.

    One of the unique aspects of this partnership has been the creation of a standardized document collection process for ALL possible loss mitigation options. Streamlining the documentation process reduces homeowner frustration and improves response times from servicers.  No longer will homeowners have to submit (and re-submit, and re-re-submit) different versions of the same documents.  This all happens ONCE - on the front end and with the assistance of a Foreclosure Counselor, and is then submitted electronically to Fannie Mae staff right here in Minnesota.  Fannie Mae staff then leverage their relationships with lenders and servicers (as the investor) to find long-term solutions.

    The Center knows that one of the greatest advantages to working with a certified non-profit Housing Counseling is that homeowners  are more successful when they have access to information and the tools necessary to get a quick response to their mortgage situation.  This new partnership takes this advantage to a whole new level.

    The services offered through this new partnership are only for borrowers who have a mortgage held by Fannie Mae. Homeowners can determine if Fannie Mae owns their loan by visiting www.fanniemae.com/loanlookup or by contacting Fannie Mae (Toll-Free) at 1-800-7FANNIE. Homeowners who do not have loans owned by Fannie Mae are still encouraged to contact a member of the Homeownership Advisors Network to learn more about their individual options to avoid foreclosure or to learn more about the foreclosure process by visiting www.hocmn.org or calling us at 866-462-6466.

    Plus:  the Center will be launching this exciting new partnership with the assistance of Fox-9 news!  Julie Gugin from the Center, and Jeff Hayward, Sr. VP from Fannie Mae, will be on the Fox-9 Morning Show from 7-9am on the Wednesday the 27th.  Other Center staff will also be featured on both the 5:00 and 9:00pm newscasts.  (Check us out after American Idol!)  We'll update this post with links to videos as soon as they are online.

    UDPATE:  Here's the piece from this morning's Fox-9 news:


    (If the embedded video doesn't work... click here to view on the Fox-9 Website.

    Wednesday, April 20, 2011

    Successful homeownership - There is a path

    Even though it might still be snowing, it really is spring in Minnesota and the only thing that appears faster than our potholes is the number of "For Sale" signs that pop up in front of homes across the state.

    Thanks to our prolonged foreclosure issues... both prices and interest rates are low.  Homeownership is more affordable now that at any other time in recent memory, and many people are thinking about becoming homeowners.  Venturing into the world of home ownership can be VERY exciting! However, it can also bring some unwelcome surprises if you're not fully prepared.

    Now, the Minnesota Home Ownership Center has prepared a new online tool that helps outline the path to successful homeownership.

    Give it a try here, and let us know what you think in the comments!

    If you're thinking about buying your first home in Minnesota... make sure you're on the right path - the path to successful home ownership.  There is tons of helpful information on the Center's website about buying your first home including information about affordable mortgages, down payment assistance and finding someone to help you through the process.  For more information, visit our website, here.

    If you're not sure what YOUR path to successful homeownership should be... or would like to speak to a FREE non-profit Housing Advisor (Housing Counselor) about YOUR next steps... visit the Center's website to connect with the agency closest to you that offers these services.

    Tuesday, April 12, 2011

    6 Days Left To Pay Your Taxes

    2010 Taxes Are Due on April 18th


    So… why are we talking about taxes on a HOUSING blog? It’s not just a simple reminder to pay your taxes - it’s a reminder that if you took advantage of the (up to) $7,500 “tax credit” on a home purchased between April 9th 2008 and July 1st 2009, your first repayment of that “tax credit” is due on your 2010 return.

    Here’s a link to our original fact sheet (created in 2008, no longer available on our website).

    Here’s the important text:
    Homeowners will have to pay it back. While these funds have been labeled a tax credit, it's really a 15 year, zero interest loan that must be paid back in equal installments over 15 years, starting in the second year after the home is purchased. If you buy a house this year and claim a $7,500 credit on your 2008 tax return, you'll have to pay an additional $500 a year in taxes for 15 years, starting in 2010.


    Time to start paying the piper.

    The SECOND tax credit, which was a maximum of $8,000 for first-time buyers who purchased between January 1st, 2009 and April 30th, 2010 (last year’s tax credit) does NOT have to be paid back via your tax returns, unless you:
    1. Sell the home within three years of purchase or the home is no longer your primary residence.
    2. If you sell within three years, and the amount you make on the sale is less than the tax credit, you only have to repay up to the amount of the gain… not the full amount.
    3. If you make MORE on the sale, or the home is no longer your primary residence, then you do owe the entire amount.
    Confused? Many people are… so make sure you speak with a qualified tax professional if you have any questions about the Homebuyer Tax Credit(s) or any amounts you may owe.